
Punjab consumer commission upholds ICICI's floating-rate hike on Rs 4 lakh home loan
The Punjab State Consumer Disputes Redressal Commission dismissed borrowers' appeal, holding that the signed loan agreement allowed ICICI to raise the interest rate and extend the loan tenure.
Key points
- The Punjab State Consumer Disputes Redressal Commission on 17 November 2026 dismissed an appeal by two home-loan borrowers.
- The borrowers said their rate rose from 9.75% to 13.50% and the loan was stretched from 180 to 347 instalments, the order records.
- The commission held the signed agreement provided for an adjustable rate; its order may be appealed.
The Punjab State Consumer Disputes Redressal Commission on 17 November 2026 dismissed an appeal by two borrowers who said ICICI had raised the interest rate on their Rs 4 lakh home loan and stretched its tenure without their consent. The commission held that the loan agreement they signed provided for an adjustable, or floating, interest rate.
What Happened
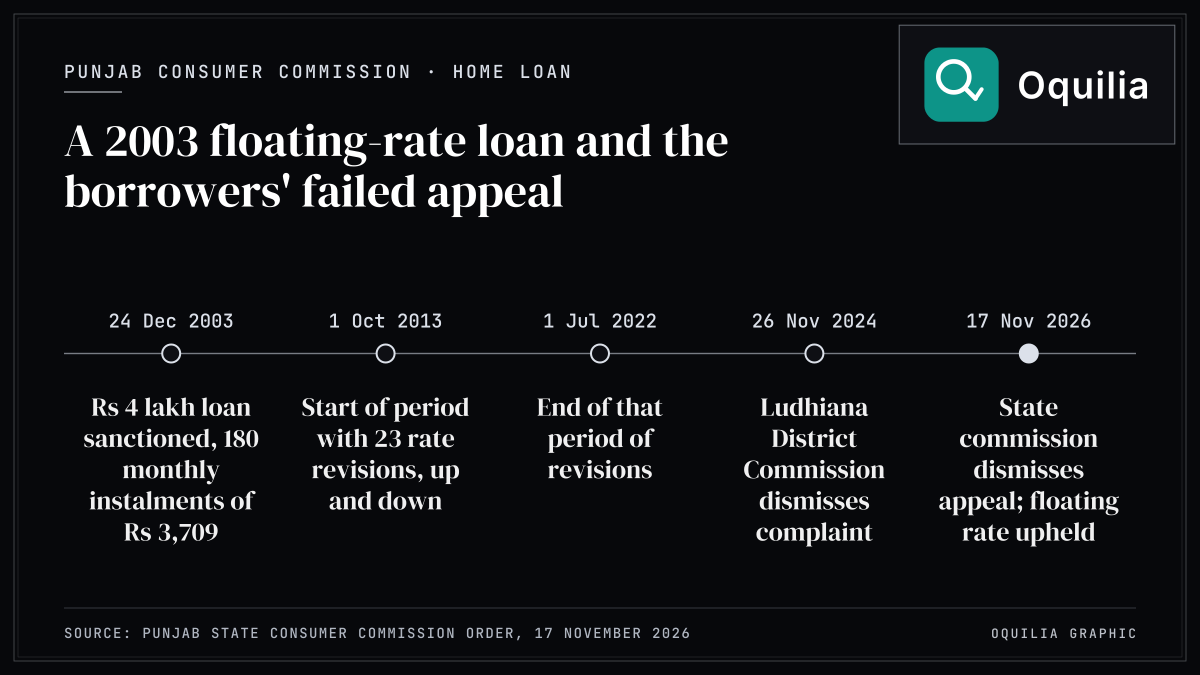
According to the order, the loan was sanctioned on 24 December 2003, repayable in 180 monthly instalments of Rs 3,709. The borrowers said they had agreed to a fixed rate of 9.75% a year, but the rate was raised to 13.50%, the instalment to Rs 4,540, and the loan rescheduled to 347 instalments ending in 2033. They said they had paid Rs 9,71,983 and sought a no-dues certificate, return of their property papers and compensation. The Ludhiana District Commission had dismissed their complaint on 26 November 2024.
The state commission found that the fixed-rate schedule in the loan papers had been crossed out and signed, and that the borrowers had signed the schedule for an adjustable interest rate. It held that the agreement allowed the lender to vary its reference rate and the instalment. It noted the District Commission's finding that the rate was revised 23 times between 1 October 2013 and 1 July 2022, both up and down, and that the lender produced letters informing the borrowers of the revisions. It also noted that the complaint was filed in 2022 for a loan taken in 2003. It found no deficiency in service or unfair trade practice. The order may be appealed before the National Consumer Disputes Redressal Commission.
What It Means
For borrowers, the ruling is a reminder that the loan papers you sign decide whether your rate is fixed or floating. On a floating-rate loan, a rise in the lender's benchmark can lengthen the tenure or raise the instalment, and consumer commissions may hold you to those terms. Keep copies of every schedule you sign, read reset letters from your lender, and check your loan statement at least once a year to see the current rate and remaining term. If a bank or housing finance company does not answer a complaint, you can approach the National Consumer Helpline on 1915 or file through e-Daakhil; complaints against banks can also go to the RBI at https://cms.rbi.org.in.
Source: Consumer commission order
Sources & Citations
- Consumer commission order — Consumer commission