
NRI life insurance payouts: when FEMA lets an Indian insurer pay the claim in foreign currency and when it must go to NRO
Under RBI's Master Direction on Insurance, a rupee life policy claim is paid in foreign currency only in proportion to premium paid in foreign currency; NRO-funded policies pay into NRO.
Key points
- The RBI Master Direction on Insurance, updated as on 7 December 2021, sets how Indian life insurers may pay claims to people resident outside India.
- On a rupee policy, foreign-currency payment is allowed only in the proportion that premium paid in foreign currency bears to total premium payable.
- Where premiums came from non-repatriable rupees, the whole claim, including a death claim to a non-resident nominee, is credited to an NRO account.
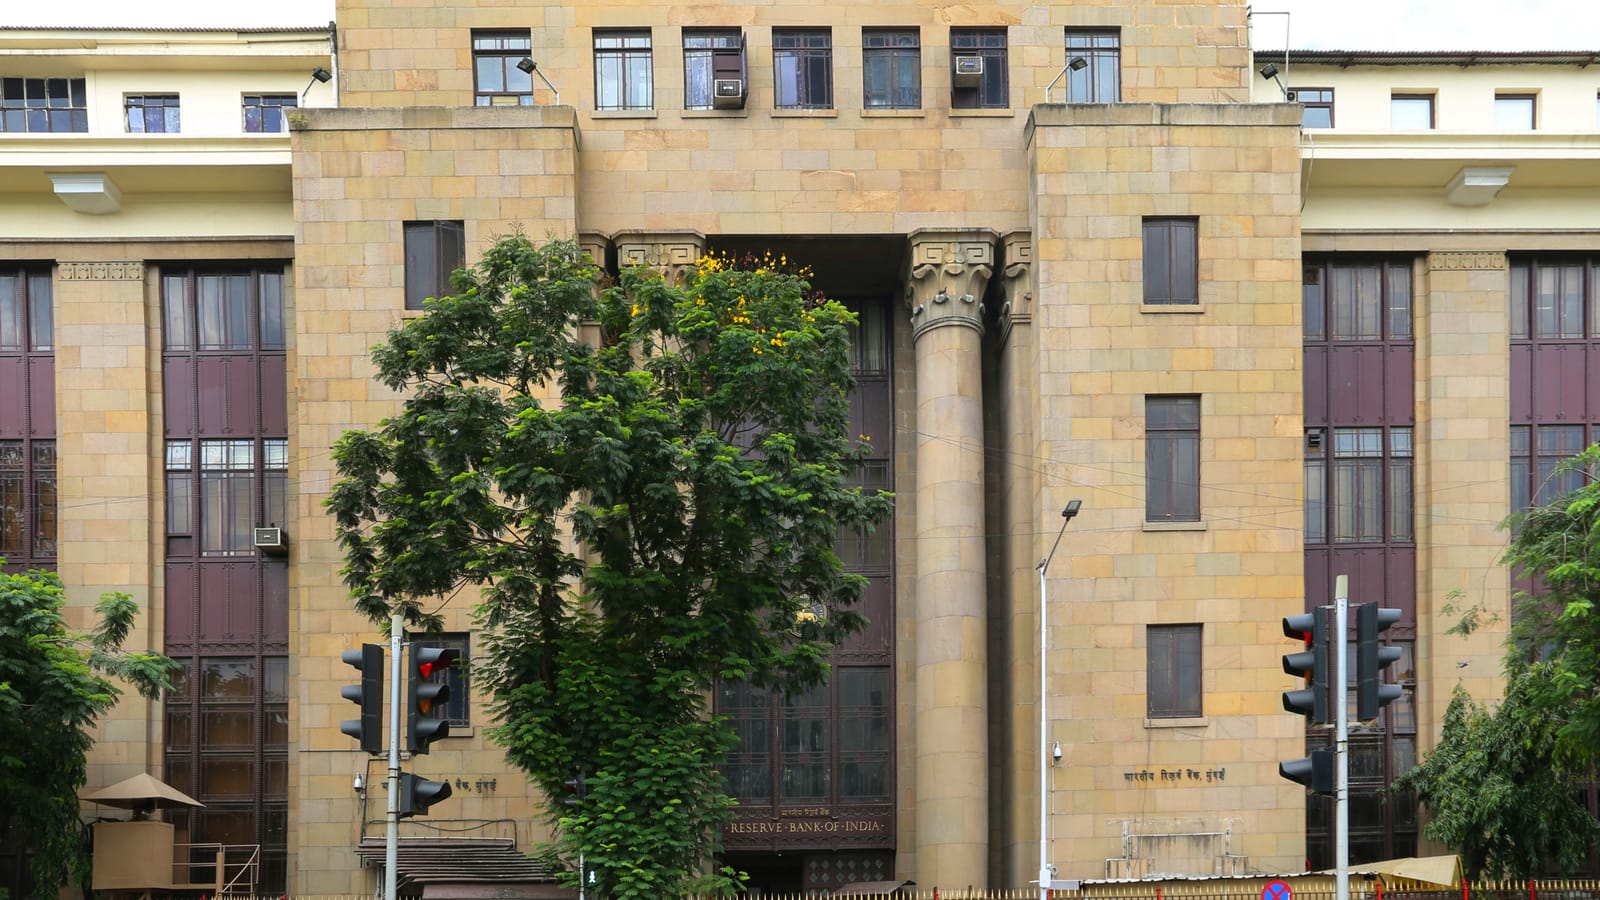
Photo: Sailko / Wikimedia Commons, CC BY 3.0 (cropped). File photo.
An Indian life insurer cannot simply wire a death claim to a nominee in Dubai or London because the nominee asks for it. The currency of the payout, and the account it lands in, are set by the Reserve Bank of India's Master Direction on Insurance (FED Master Direction No. 9/2015-16, RBI/FED/2015-16/5), dated 1 January 2016 and updated as on 7 December 2021. Part 4 of that Direction, which deals with life insurance taken from insurers in India, links the claim route to one question above all others: in what currency, and from which account, were the premiums paid?
This explainer walks through that rule for non-resident Indians (NRIs), Overseas Citizens of India (OCIs) and their families. It covers the FEMA payment route only. It does not set out how maturity or death proceeds are taxed in India or abroad, and readers should not read any part of it as a statement on tax.
FEMA / DTAA Position
The Master Direction is issued under Section 47(2) of the Foreign Exchange Management Act, 1999 (FEMA), read with Notification No. FEMA 12(R)/2015-RB. Section 6 of FEMA, according to Oquilia's statute brief, requires RBI permission for capital account dealings unless they are specifically permitted, which is why insurance flows across borders need a written route rather than an assumption. The Direction is that written route for insurance. It is a foreign-exchange rule, not a tax treaty, so no Double Taxation Avoidance Agreement (DTAA) changes which account an insurer may credit.
The Direction treats the premium and the claim as two halves of the same transaction. Paragraph 4.2(b) sets out how a person resident outside India may pay premiums, and paragraph 4.3 sets out how the claim, maturity value or surrender value may be paid back. The three premium routes in paragraph 4.2(b) are summarised below.
| Para | Policy type | How premium may be paid | Who issues |
|---|---|---|---|
| 4.2(b)(i) | Foreign-currency-denominated policy | In foreign currency from abroad, or out of NRE/FCNR accounts of the insured or his family members held in India | Insurer in India, through offices in India or abroad |
| 4.2(b)(ii) | Rupee-denominated policy issued to a resident outside India | Funds in NRO accounts can be accepted | Insurer in India |
| 4.2(b)(iii) | Policy issued abroad to Indian nationals/OCIs by an overseas office of an Indian insurer | Foreign currency, while abroad | Overseas office of an Indian insurer |
Under paragraph 4.2(b)(i), an Indian insurer may issue a policy denominated in a foreign currency to a person resident outside India. Two conditions attach: the premium must be collected in foreign currency remitted from abroad, or out of the NRE or FCNR accounts of the insured or his family members held in India. Both sources are repatriable money, which is why the claim on such a policy can travel back out in foreign currency.
Under paragraph 4.2(b)(ii), for a rupee-denominated policy issued to a resident outside India, the insurer may accept premium from funds in an NRO account. NRO money is, by design, non-repatriable rupee money, and that single choice of account at the premium stage has consequences at the claim stage that many families discover only after a death.
Paragraph 4.2(b)(iii) deals with the returning NRI. A policy issued to an Indian national or OCI abroad by the overseas office of an Indian insurer may be transferred to the Indian register on return to India. Foreign currency policies are then converted into rupee policies, unless the policy has been in force for at least 3 years before return and the holder wishes to continue it. In that case foreign currency premium payments are allowed, provided the holder undertakes to repatriate maturity or claim proceeds to India within 7 days of receipt.
Finally, the Direction draws a firm line on one move: converting a rupee policy of a resident into a foreign currency policy needs prior RBI approval. An insurer cannot do it on request, and a policyholder who has been resident in India for the life of the policy cannot shift it into dollars because a nominee has since moved abroad.
Tax Treatment in India
The Master Direction of 1 January 2016 is silent on income tax, and this article follows that boundary: it does not state whether a maturity value, surrender value or death claim is taxable, exempt or subject to any particular rate. Those questions are governed by the Income-tax Act, 1961, not by FEMA, and the answer turns on facts (policy date, sum assured, premium history, residential status) that a payment-route rule does not capture.
What can be said with confidence is procedural. Section 195 of the Income-tax Act, 1961 is the withholding provision for sums paid to non-residents, and according to Oquilia's statute brief it requires withholding at the DTAA rate or the rate in the Act, whichever is lower, where withholding applies at all. Whether any part of a particular insurance payout is a "sum chargeable" for Section 195 is a question for the insurer's tax team and the claimant's adviser, and readers can check their position using the NRI income tax calculator.
A second procedural point flows from the FEMA rules themselves. Because paragraph 4.3(i) can split a single claim into a foreign-currency part and a rupee part, the insurer's settlement letter may show two figures, two dates and two receiving accounts. Claimants should keep that letter with their tax records for the financial year in which each credit lands, since a payout in the 2026-27 financial year (1 April 2026 to 31 March 2027) is reported for that year whatever the currency.
Readers looking for the general framework of withholding on non-resident income can see the TDS glossary entry, and the official Income Tax Department portal at incometax.gov.in carries the text of the Act and current forms. Nothing in this section should be read as a view on whether a life insurance payout attracts tax.
Tax Treatment Abroad
How a country of residence treats an Indian life insurance payout is a matter of that country's domestic law and of the DTAA it has signed with India. The RBI Master Direction does not address foreign tax, and this article does not attempt a country-by-country view. A claimant in the United States, the United Kingdom, the UAE, Canada, Singapore or Australia should take advice under the rules of that jurisdiction for the year of receipt.
The interaction that matters most is foreign tax credit. If India withholds tax on a payment under Section 195 of the Income-tax Act, 1961, the claimant's country of residence may or may not allow a credit for it, depending on its treaty with India and its own rules. Oquilia's foreign tax credit calculator and the DTAA glossary entry explain how credits generally work, but they do not decide whether insurance proceeds are covered in a given treaty.
One FEMA fact does affect paperwork abroad. A claim paid partly in foreign currency under paragraph 4.3(i) and partly into an NRO account under paragraph 4.3(iv) produces two separate receipts. The foreign-currency part may reach an NRE or FCNR account under paragraph 4.3(ii), while the rupee part remains in India until it is repatriated, so the date on which money is "received" abroad can differ by weeks or months between the two parts.
Repatriation Mechanics
This is the heart of the rule. Paragraph 4.3 of the Master Direction sets out five situations, and each one names the currency and the account. The table below lays them side by side.
| Para | Situation | Currency of payout | Receiving account |
|---|---|---|---|
| 4.3(i) | Rupee life policy, claimant resident outside India | Foreign currency only in proportion that premium paid in foreign currency bears to total premium payable | Balance in rupees |
| 4.3(ii) | Claim, maturity or surrender value settled in foreign currency, beneficiary non-resident | Foreign currency | May be credited to NRE/FCNR account |
| 4.3(iii) | Foreign-currency settlement, beneficiary resident; or returning Indian | Foreign currency | RFC (Domestic) account; returning Indians to their RFC account |
| 4.3(iv) | Rupee policy of Indian resident outside India, premiums paid in non-repatriable rupees | Rupees only | Beneficiary's NRO account, including death claims to non-resident nominees/assignees |
| 4.3(v) | Rupee policy of a foreign national not permanently resident in India | Rupees, or remitted abroad | As settled |
The proportion rule in paragraph 4.3(i)
The proportion rule is easiest to see with numbers. Take an illustrative rupee policy with total premium payable of Rs 10,00,000 and a death claim of Rs 25,00,000. If Rs 6,00,000 of the premium was paid in foreign currency and Rs 4,00,000 from non-repatriable rupee funds, foreign-currency premium is 60% of the total.
| Item | Illustrative figure |
|---|---|
| Total premium payable | Rs 10,00,000 |
| Premium paid in foreign currency | Rs 6,00,000 (60%) |
| Premium paid in non-repatriable rupees | Rs 4,00,000 (40%) |
| Death claim on the rupee policy | Rs 25,00,000 |
| Maximum payable in foreign currency under para 4.3(i) | Rs 15,00,000 equivalent (60%) |
| Balance payable in rupees | Rs 10,00,000 (40%) |
These figures are illustrative only and are not drawn from any insurer's records. The point is the ratio: under paragraph 4.3(i), the foreign-currency share of the claim cannot exceed the foreign-currency share of the premium, however large the claim. A policy funded 100% from abroad can, on this logic, be paid 100% in foreign currency, while a policy funded 0% from abroad cannot be paid any part in foreign currency.
When the whole claim goes to NRO
Paragraph 4.3(iv) is the strict end of the scale. Where premiums on a rupee policy issued to an Indian resident outside India were collected in non-repatriable rupees, the claim, maturity value or surrender value is paid only in rupees, by credit to the beneficiary's NRO account. The Direction states expressly that this includes death claims paid to non-resident nominees or assignees, so a nominee abroad cannot ask the insurer to remit the money directly.
Money credited to an NRO account is not trapped forever. It sits in a separate repatriation regime under FEMA, and Oquilia's repatriation calculator and NRO to NRE transfer calculator set out how funds can later be moved out. That is a second, separate step, governed by different rules from the 2016 Master Direction on Insurance, and it typically involves the bank and the documents it asks for.
Foreign-currency settlements: NRE, FCNR and RFC
When a claim, maturity value or surrender value is settled in foreign currency, paragraph 4.3(ii) lets a non-resident beneficiary credit it to an NRE account or an FCNR deposit. Both are repatriable, so the money keeps the character it had when the premium was paid from abroad.
Paragraph 4.3(iii) covers the beneficiary who is resident in India. A resident who receives a foreign-currency settlement may credit it to an RFC (Domestic) account, and a returning Indian may credit it to his RFC account. This is the route that closes the loop for paragraph 4.2(b)(iii), where a returning policyholder who kept a foreign-currency policy undertook to bring claim proceeds into India within 7 days of receipt.
Foreign nationals
Paragraph 4.3(v) applies to rupee policies held by foreign nationals not permanently resident in India. Claims on such policies may be paid in rupees or remitted abroad. This is a narrower group than NRIs or OCIs, and the paragraph should not be read across to Indian citizens living abroad, whose rupee policies fall under paragraph 4.3(i) or 4.3(iv).
The full text is on the RBI website as the Master Direction - Insurance, and the wider framework is explained in Oquilia's FEMA glossary entry.
FAQ
Can an Indian insurer pay a death claim directly into my bank account abroad?
Only to the extent the Master Direction of 1 January 2016 allows foreign-currency payment. On a rupee policy, paragraph 4.3(i) limits the foreign-currency share to the proportion of premium paid in foreign currency. If all premiums came from non-repatriable rupees, paragraph 4.3(iv) requires the whole claim to be credited to the beneficiary's NRO account.
My father paid premiums from his NRO account. Where will the claim go?
Paragraph 4.2(b)(ii) allows NRO funds to be accepted as premium on rupee policies issued to residents outside India. Under paragraph 4.3(iv), where premiums were collected in non-repatriable rupees, the claim is paid only in rupees by credit to the beneficiary's NRO account, and this includes death claims to non-resident nominees or assignees.
What happens if premiums were paid partly from NRE and partly from NRO?
Paragraph 4.3(i) applies the proportion rule. If, for example, 60% of total premium payable was paid in foreign currency, up to 60% of the claim on a rupee policy can be paid in foreign currency to a claimant resident outside India, with the balance in rupees.
Can a foreign-currency policy be paid into an NRE or FCNR account?
Yes. Under paragraph 4.3(ii), non-resident beneficiaries of claims, maturity values or surrender values settled in foreign currency may credit them to NRE or FCNR accounts. Such policies are issued under paragraph 4.2(b)(i), where premium is paid in foreign currency from abroad or from NRE/FCNR accounts of the insured or his family members.
I am returning to India. Can I keep my foreign-currency policy?
Under paragraph 4.2(b)(iii), a policy issued abroad by an Indian insurer's overseas office may be moved to the Indian register on return. It is converted into a rupee policy unless it has been in force for at least 3 years before return and you wish to continue it, in which case you must undertake to repatriate claim or maturity proceeds to India within 7 days of receipt.
Can a resident convert a rupee policy into dollars because the nominee lives abroad?
No, not without the regulator. The Master Direction states that converting rupee policies of residents into foreign currency needs prior RBI approval. An insurer cannot make the change on request.
Does this article explain how the payout is taxed?
No. This article covers the FEMA payment route under the RBI Master Direction updated as on 7 December 2021. Tax on maturity, surrender or death proceeds is governed by the Income-tax Act, 1961 and the tax law of the country of residence, and claimants should take specific advice.
Sources & Citations
- Master Direction - Insurance (FED Master Direction No. 9/2015-16) — Reserve Bank of India
- Income Tax Department e-filing portal — Income Tax Department