

NCDRC rejects United India Insurance's denial of 2010 factory fire claim
The National Consumer Disputes Redressal Commission held that a 2010 factory fire was accidental and directed United India Insurance to assess the loss and inform the policyholder within three months.
Key points
- The National Consumer Disputes Redressal Commission on 16 November 2026 held United India Insurance's 2011 rejection of a fire claim unsustainable.
- The insurer must get the loss assessed from the material on record and tell the policyholder the outcome within three months, the commission ordered.
- The commission held that an insurer is liable for an accidental fire even if its cause stays undetermined, and a surveyor must assess the loss.
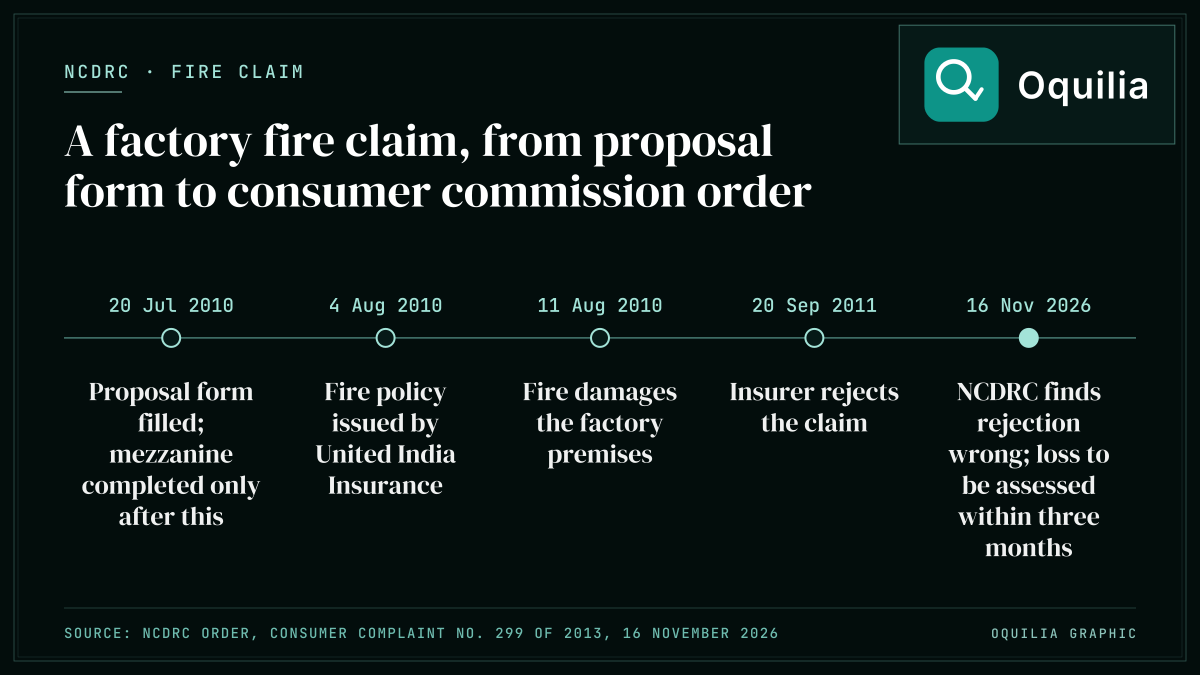
The National Consumer Disputes Redressal Commission has held that United India Insurance Company was wrong to reject a fire claim by Dee Tex Poly Yarn Pvt. Ltd. on the grounds it gave, and has directed the insurer to assess the loss. The order in Consumer Complaint No. 299 of 2013 was pronounced on 16 November 2026.
What Happened
The company's factory premises were damaged in a fire on 11 August 2010, days after a fire policy was issued on 4 August 2010. The insurer rejected the claim on 20 September 2011, saying the company had built a mezzanine floor without its sanction, had not disclosed another policy in the proposal form, and that the circumstances of the fire were doubtful.
The commission held that the fire was in all probability an accident and that there was no evidence it was started deliberately by the policyholder. Where the cause of a fire is indeterminate and no material shows it was deliberate, the insurer is liable, the commission said. It found the suggestion in the rejection letter that an eyewitness had been tutored was a surmise.
On the mezzanine platform, the commission found that it was completed after the proposal form was filled on 20 July 2010, so it was neither a breach of the policy terms nor a material non-disclosure.
The commission also found that the surveyor had not assessed the loss, and called this a further deficiency under Section 64UM of the Insurance Act, 1938 and the IRDA surveyor regulations, which oblige a surveyor to carry out an assessment.
What It Means
The commission partly allowed the complaint. United India Insurance may have the loss assessed by another surveyor, or do it itself in consultation with the surveyor, on the basis of the material on record, and must tell the policyholder the outcome within three months. The commission did not itself fix an amount.
For policyholders, the order is a reminder that an insurer has to stand by the reasons it gives in its rejection letter, and that a surveyor's report must assess the loss. A consumer commission's order may be appealed. Complaints against an insurer can be filed through e-Daakhil or the National Consumer Helpline on 1915.
Source: Consumer commission order
Sources & Citations
- Consumer commission order — Consumer commission