
NCDRC orders Oriental Insurance to reassess fire claims it had rejected over fake bills
The National Consumer Disputes Redressal Commission held that Oriental Insurance wrongly rejected seven fire claims from Bikaner units on a surveyor's suspicion, and ordered payment with 9% interest.
Key points
- The NCDRC held on 11 November 2026 that Oriental Insurance's rejection of seven fire insurance claims was a deficiency in service.
- The commission ordered the claims reassessed and paid with 9% yearly interest from 2 September 2014, plus Rs 25,000 costs to each complainant.
- The commission said a surveyor's suspicion alone cannot justify rejecting a claim for a loss that admittedly occurred.
The National Consumer Disputes Redressal Commission (NCDRC) has held that The Oriental Insurance Company wrongly rejected fire insurance claims from seven fuel-briquette makers in Bikaner, Rajasthan. In an order pronounced on 11 November 2026, the commission directed the insurer to reassess the losses and pay them with 9% yearly interest from 2 September 2014, the date of the rejection.
What Happened
The seven units held Standard Fire and Special Perils policies covering their stock of agricultural waste and briquettes, with add-on cover for spontaneous combustion and storage in open land. A fire in their industrial area on 13 May 2013 destroyed the stock. Oriental Insurance rejected the claims on 2 September 2014, saying documents were not supplied and that purchase bills were fake, according to the order.
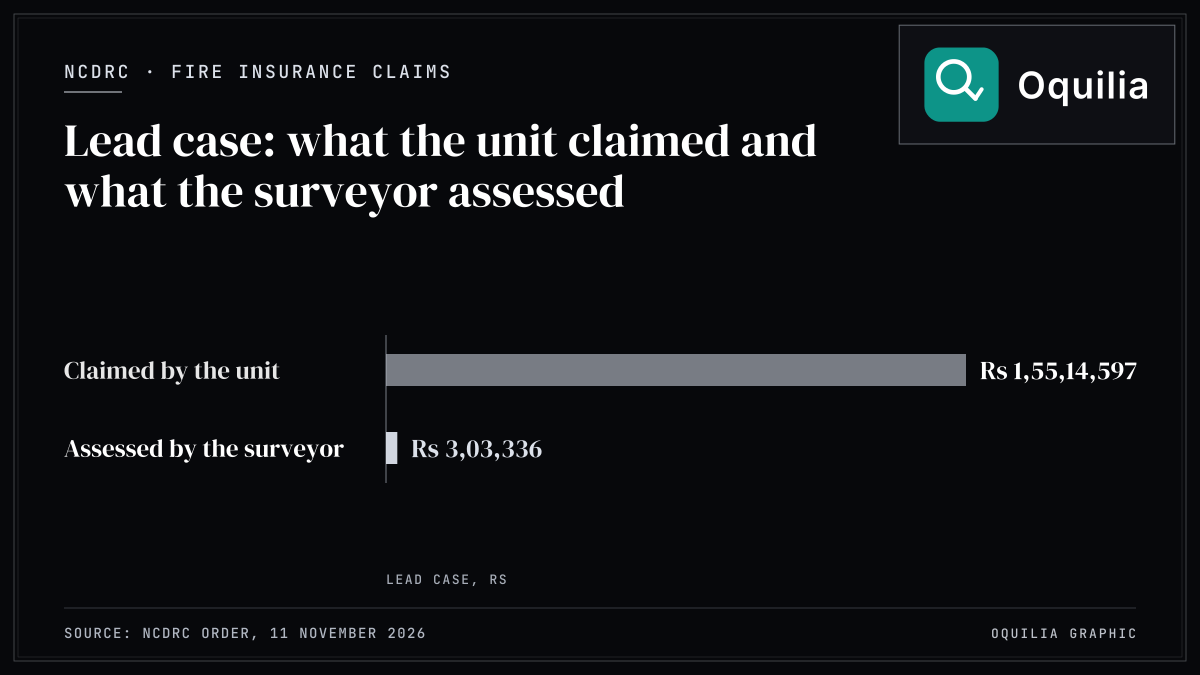
The commission held that the fake-bills ground rested only on the surveyor's apprehension, without any independent investigation. It noted that a price difference of less than 10% between two buyers cannot by itself show bills were fake. It relied on stock statements the units had filed with their lender, Punjab National Bank, about a week before the fire; the bank confirmed them. In the lead case, the claim was Rs 1,55,14,597, the surveyor assessed Rs 3,03,336, and the bank stock statement showed stock valued at over Rs 90 lakh. Citing the Supreme Court, the commission said a surveyor's report is not sacrosanct.
What It Means
The insurer must hear each complainant within one month of receiving the certified order, using the surveyor's figure as the minimum, and pay within two months, failing which interest rises to 12% a year. Each complainant also gets Rs 25,000 as litigation costs. In three cases, the payout first settles dues to the bank. The order may be appealed.
For policyholders, the order holds that mere suspicion of fraud cannot be the basis to deny a genuine claim. A policyholder whose claim is rejected can approach a consumer commission through e-Daakhil or the National Consumer Helpline (1915).
Source: Consumer commission order
Sources & Citations
- Consumer commission order — Consumer commission