
Foreign Retirement Account Income in ITR-2: Section 89A Relief, Form 10EE and the AY 2026-27 Validation Checks
How residents defer tax on US, UK and Canadian retirement account income under section 89A, file Form 10-EE, and clear the nine ITR-2 validation checks for AY 2026-27.
Key points
- CBDT's ITR-2 validation rules for AY 2026-27, Version 1.0 dated 26 May 2026, set nine checks on section 89A relief for foreign retirement accounts.
- Relief cannot exceed the income offered, each country may be entered only once, and an HUF cannot claim the relief at all.
- Taxpayers must file Form 10-EE with the relief amount before the return, or the return may fail to upload or the claim may be disallowed.
If you came back to India after working in the United States, the United Kingdom or Canada, your old retirement account abroad may still be earning income every year. Section 89A of the Income-tax Act, 1961 lets a resident defer Indian tax on that income until the foreign country taxes it. On 26 May 2026 the Directorate of Income Tax (Systems) published Version 1.0 of the ITR 2 Validation Rules for AY 2026-27. At least nine of its checks govern how this relief is reported. Several of them are Category A rules, which stop the e-Filing portal from accepting the return at all.
This guide sets out what section 89A says, how the ITR-2 schedules have to add up, and the mistakes that trigger the errors.
What the Section Says
Section 89A was inserted by the Finance Act, 2021, with effect from assessment year 2022-23. Its main sub-section is a single sentence: the income of a "specified person" from a "specified account" is taxed in the manner and in the year that the Central Government prescribes. The definitions sit in the Explanation to the section.
| Term in section 89A | Plain-English meaning |
|---|---|
| Specified person | A person resident in India who opened the account in a notified country while non-resident in India and resident in that country |
| Specified account | An account in a notified country, held for retirement benefits, whose income is not taxed there on accrual but on withdrawal or redemption |
| Notified country | A country notified by the Central Government in the Official Gazette for section 89A |
The government prescribed the method through Rule 21AAA and Form No. 10-EE, notified by CBDT in Notification No. 24/2022 dated 4 April 2022. A separate notification, No. 25/2022 of the same date, named the notified countries: Canada, the United Kingdom of Great Britain and Northern Ireland, and the United States of America. An account in any other country does not qualify for section 89A relief.
Under Rule 21AAA, income that accrues in the specified account goes into your Indian total income for the previous year in which the notified country taxes it, which is normally the year you withdraw or redeem. You choose this treatment by e-filing Form No. 10-EE on or before the date you file your return. Once you exercise the option, it applies to all later previous years and cannot be withdrawn. The rule also covers what happens if you become non-resident after opting in, so read that sub-rule before you rely on the deferral long term.
The relief is a deferral, not a waiver. In the year the notified country taxes the withdrawal, the deferred income comes into your Indian return. Until then, section 89A stops you from paying Indian tax each year on growth that the foreign country has not yet taxed.
For tax years from 1 April 2026, the Income-tax Act, 2025 carries this relief in section 158. Under the Income-tax Rules, 2026, the option form becomes Form No. 40 (formerly 10-EE). AY 2026-27 returns, which cover FY 2025-26, are still filed under the 1961 Act, so Form 10-EE and section 89A are the references for the return you file this year.
Where the relief sits in ITR-2
ITR-2 reports this income in two places, depending on its character. Schedule Salary has an income field at serial 1d with country drop-downs. Schedule Other Sources (OS) takes the income at serial 1e, "Income from retirement benefit account maintained in a notified country u/s 89A", and the relief at serial 5a, "Income claimed for relief from taxation u/s 89A". You can see what each field holds in the department's ITR-2 online filing manual.
The AY 2026-27 validation checks
The table below lists every section 89A rule in the 26 May 2026 document. Rule numbers 59 to 232 are Category A, which means the return will not upload until the error is fixed. Rule 19 in the Category B/D table lets the return upload but warns that the claim may not be allowed.
| Rule | Schedule | What the validation checks | Category |
|---|---|---|---|
| 59 | Salary | An HUF cannot claim relief under section 89A | A |
| 60 | Salary | Relief claimed cannot exceed income offered at serial 1d | A |
| 65 | Salary | Each country can be selected only once in the country drop-down | A |
| 224 | OS | Relief claimed cannot exceed the income offered from the notified-country account | A |
| 225 | OS | The quarterly breakup must equal the account income less the relief claimed | A |
| 226 | OS | Relief at serial 5a is allowed only if income is offered at serial 1e | A |
| 227 | OS | Total account income must equal the sum of the country-wise amounts | A |
| 232 | OS | Each country can be selected only once in the country drop-down | A |
| 19 | General | Form 10EE should be filed with the amount of income claimed for relief | B/D |
Rule 206 adds one more link. In Schedule OS, income chargeable at normal rates is computed after subtracting "Income claimed for relief from taxation u/s 89A". So every rupee you claim at serial 5a reduces the amount that goes into your slab calculation.
Worked Example
Take a hypothetical resident individual, Ms A, filing ITR-2 for AY 2026-27 under the new regime. She worked in the United States and the United Kingdom before returning to India and becoming resident. During FY 2025-26 she withdrew nothing from either retirement account.
| Item (FY 2025-26) | Amount (Rs) |
|---|---|
| Gross salary in India | 18,00,000 |
| Standard deduction, new regime | 75,000 |
| Accrued income, US retirement account | 4,20,000 |
| Accrued income, UK retirement account | 1,10,000 |
| Total notified-country account income | 5,30,000 |
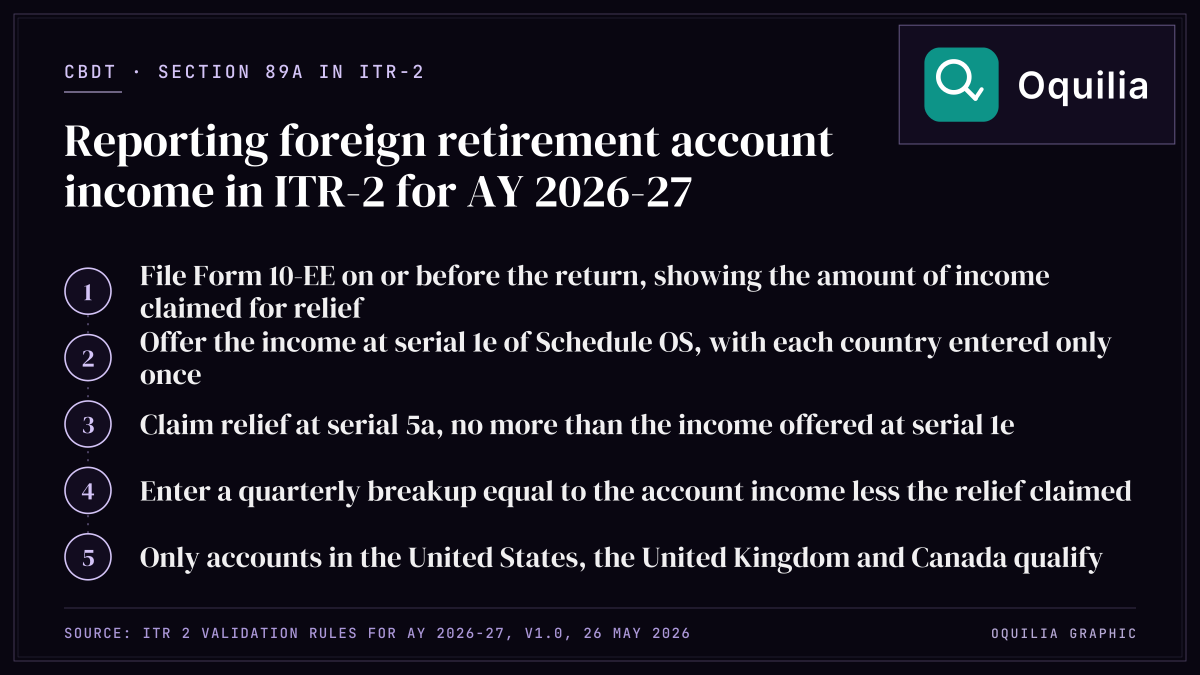
Step 1: file Form 10-EE. Ms A e-files Form 10-EE showing Rs 5,30,000, the amount she will claim as relief, before she files the ITR. Validation rule 19 links the two figures.
Step 2: offer the income at serial 1e of Schedule OS. She makes two country rows: United States Rs 4,20,000 and United Kingdom Rs 1,10,000. Each country appears once (rule 232), and the total of Rs 5,30,000 equals the sum of the rows (rule 227).
Step 3: claim relief at serial 5a. She claims Rs 5,30,000. This is allowed because the income is already offered at 1e (rule 226) and the claim does not exceed it (rule 224).
Step 4: the quarterly breakup. The breakup must equal Rs 5,30,000 less Rs 5,30,000, which is Rs 0 (rule 225).
The tax effect, using the FY 2025-26 new-regime slabs (nil up to Rs 4 lakh, then 5%, 10%, 15%, 20% and 25% in Rs 4 lakh bands, 30% above Rs 24 lakh) and 4% health and education cess:
| Computation | With section 89A relief | Without relief |
|---|---|---|
| Taxable income | Rs 17,25,000 | Rs 22,55,000 |
| Slab tax | Rs 1,45,000 | Rs 2,63,750 |
| Cess at 4% | Rs 5,800 | Rs 10,550 |
| Total tax | Rs 1,50,800 | Rs 2,74,300 |
Here is the slab working for the relief column. Rs 20,000 on the Rs 4-8 lakh band, Rs 40,000 on the Rs 8-12 lakh band, Rs 60,000 on the Rs 12-16 lakh band and Rs 25,000 on the remaining Rs 1,25,000 at 20% give Rs 1,45,000. In this year the deferral keeps Rs 1,23,500 of tax out of the return. That tax comes due in the year the US or UK taxes the withdrawal. You can test your own figures in the new-regime income tax calculator. Taxable income here is above Rs 12 lakh, so the section 87A rebate (up to Rs 60,000 in the new regime) does not apply.
Common Mistakes
1. Claiming relief without offering the income. Rule 226 rejects a figure at serial 5a when serial 1e is blank. The relief has to be set against income you have actually reported. You cannot claim it on its own.
2. Claiming more relief than income. Rules 60 and 224 cap the relief at the income offered, in Schedule Salary and Schedule OS respectively. A Rs 5,40,000 claim against Rs 5,30,000 of income will not upload.
3. Splitting one country across two rows. People with two US accounts often enter "United States" twice. Rules 65 and 232 allow each country only once, so add up all accounts in the same country and enter one row.
4. Country totals that do not add up. Under rule 227, the headline figure has to equal the sum of the country rows exactly. A rounding difference of even Rs 1 fails the check.
5. Leaving the quarterly breakup at the gross figure. Rule 225 expects the quarterly figures to add up to the income net of relief. If you claim full relief, the breakup should total Rs 0.
6. Filing as an HUF. Rule 59 blocks an HUF from claiming the relief. The section is limited to the person who opened the account, so the claim belongs in the individual's own return.
7. Skipping Form 10-EE. Rule 21AAA says the option is exercised through Form 10-EE furnished on or before the return. Validation rule 19 warns that the 10-EE amount should match the claim. Without the form, the deferral has no legal basis.
8. Using the relief for accounts outside the three notified countries. Notification No. 25/2022 names only Canada, the UK and the US. You cannot use section 89A for accounts in other countries. If you were a non-resident there, check your residential status and whether the relevant DTAA applies.
Before filing, compare regimes in the old vs new regime calculator, and use the income tax calculator to check the slab working above.
FAQ
Which countries are notified under section 89A?
Notification No. 25/2022 dated 4 April 2022 notified Canada, the United Kingdom of Great Britain and Northern Ireland, and the United States of America. Retirement accounts in any other country do not qualify for this relief.
Is section 89A relief an exemption?
No. Under Rule 21AAA, the income is taxed in India in the previous year in which the notified country taxes it, which is usually the year of withdrawal. The section changes when the income is taxed. It does not remove the tax.
When must Form 10-EE be filed?
Rule 21AAA requires Form 10-EE to be e-filed on or before the date you file your income tax return. The amount on the form should match the relief claimed in ITR-2, as validation rule 19 of the 26 May 2026 document points out.
Can I withdraw the option once exercised?
No. Once the option is exercised through Form 10-EE, it applies to all later previous years and cannot be withdrawn under Rule 21AAA.
Can an HUF claim section 89A relief?
No. Rule 59 of the AY 2026-27 ITR-2 validation rules says an HUF cannot claim relief under section 89A, and the section defines the specified person as the individual who opened the account.
What changes under the Income-tax Act, 2025?
For tax years from 1 April 2026, the relief moves to section 158 of the Income-tax Act, 2025. Under the Income-tax Rules, 2026, the option form becomes Form No. 40 (formerly 10-EE). AY 2026-27 returns covering FY 2025-26 still use section 89A and Form 10-EE.
What if I hold two accounts in the same country?
Add them together. Rules 65 and 232 allow each country only once in the drop-down, and rule 227 requires the total to equal the sum of the country rows.
Sources & Citations
- ITR 2 - Validation Rules for AY 2026-27, Version 1.0 (26 May 2026) — Income Tax Department
- File ITR-2 Online User Manual — Income Tax Department