
CBDT Circular 6/2026: Late Form 10AB Filings for 80G Renewal Condoned, Orders Due by 31 December 2026
CBDT Circular 6/2026 condones late Form 10AB filings made between 1 October 2025 and 31 March 2026 for 80G renewal. Commissioners must decide on merits by 31 December 2026.
Key points
- CBDT has condoned the delay for funds and institutions that filed Form 10AB for 80G renewal late, through Circular No. 6/2026 issued in July 2026.
- The relief covers Form 10AB filed between 1 October 2025 and 31 March 2026, after the 30 September 2025 due date for approvals expiring on 31 March 2026.
- Commissioners must decide each application on merits by 31 December 2026, and the circular gives no automatic right to 80G approval.
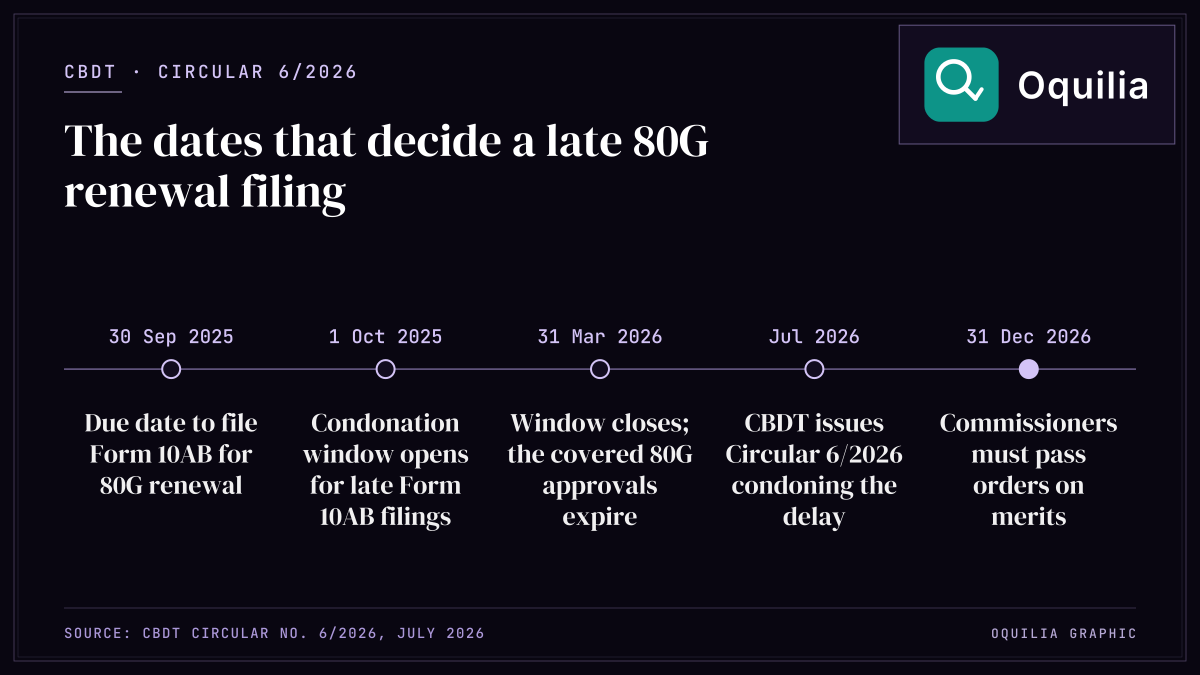
The Central Board of Direct Taxes (CBDT) has issued Circular No. 6/2026 (F. No. 300176/3/2026-ITA-I, July 2026), condoning the delay for charitable funds and institutions that missed the 30 September 2025 deadline to file Form No. 10AB for renewal of their section 80G approval. The relief covers applications furnished electronically between 1 October 2025 and 31 March 2026, and the jurisdictional Principal Commissioners or Commissioners of Income-tax must pass orders on them by 31 December 2026.
For donors, this matters because section 80G of the Income-tax Act, 1961 only allows a tax deduction for donations to funds and institutions that hold a valid approval. For the institutions, the circular is the difference between a fresh hearing and a closed door. The full text is available on the Income Tax Department portal.
What the Section Says
Section 80G of the Income-tax Act, 1961 provides for a deduction in respect of donations made to certain funds and institutions. Depending on the institution, the deduction is either 50% or 100% of the eligible donation, and it is available only under the old tax regime, not the new regime.
The approval that makes a donation deductible is granted under section 80G(5). That approval runs for a fixed period. Under clause (ii) of the first proviso to section 80G(5), a fund or institution whose approval is due to expire must furnish an application in Form No. 10AB electronically at least six months before the expiry date.
For the large group of institutions whose approval was expiring on 31 March 2026, six months before expiry meant a due date of 30 September 2025. According to paragraph 2 of the circular, CBDT received representations from several funds and institutions that could not file within that date, citing bona fide reasons and genuine hardship in receiving donations.
CBDT has acted under section 119(2)(b) of the Income-tax Act, 1961, read with section 536(2) of the Income-tax Act, 2025. Section 119(2)(b) is the Board's power to authorise admission of an application after the prescribed time to avoid genuine hardship. The reference to section 536(2) of the 2025 Act reflects the transition to the new statute, which carries the equivalent approval provision in section 133(1)(b).
The circular does four things, set out in the table below.
| Para | What CBDT decided | Key date |
|---|---|---|
| 3 | Delay condoned where Form 10AB was filed electronically in the window | 01.10.2025 to 31.03.2026 |
| 3 | Pr. CIT / CIT to decide such applications on merits | Order by 31.12.2026 |
| 4 | Applications already rejected solely for being late are deemed condoned | Rejection on or before the circular's issue |
| 5 | No automatic entitlement to approval under 80G(5) or 133(1)(b) of the 2025 Act | Not applicable |
Paragraph 5 is the one institutions should read twice. Condonation only removes the time bar; it does not grant approval. The Commissioner still examines each application on merits before 31 December 2026.
Worked Example
The examples below use the dates in the circular and, for the donor's tax saving, the FY 2025-26 old-regime slab rates and 4% health and education cess from Oquilia's rate configuration.
Case A: the institution. A trust in Pune held a section 80G(5) approval expiring on 31 March 2026. Its due date for Form 10AB was therefore 30 September 2025. The trust's accountant filed Form 10AB electronically on 14 January 2026, 106 days late.
Under paragraph 3 of Circular 6/2026, the filing date of 14 January 2026 falls inside the 1 October 2025 to 31 March 2026 window, so the delay is condoned. The Commissioner must now decide the application on merits and pass an order by 31 December 2026.
Case B: the rejected application. A second trust filed Form 10AB on 20 February 2026. In May 2026, before the circular was issued, its application was rejected, and the only ground in the order was that it had been filed after 30 September 2025.
Paragraph 4 treats the delay as deemed condoned. The trust does not need to show fresh hardship; the Commissioner must take up the application on merits and pass an order by 31 December 2026. If the rejection order had also cited a ground other than the delay, paragraph 4 would not apply, because it covers rejections made "solely" on the time-limit ground.
Case C: outside the window. A third trust filed Form 10AB on 4 April 2026, four days after the window closed on 31 March 2026. Circular 6/2026 does not cover it. That trust would have to rely on any separate remedy available to it; this circular gives it nothing.
| Trust | Approval expiry | Form 10AB filed | Covered by Circular 6/2026? | Order due by |
|---|---|---|---|---|
| A | 31.03.2026 | 14.01.2026 | Yes, para 3 | 31.12.2026 |
| B | 31.03.2026 | 20.02.2026, rejected for delay only | Yes, para 4 (deemed condoned) | 31.12.2026 |
| C | 31.03.2026 | 04.04.2026 | No | Not applicable |
The donor's side. Ravi is a salaried employee in the old regime with taxable income above Rs 10 lakh, so his marginal slab rate under the FY 2025-26 old-regime slabs is 30%. He donates Rs 50,000 by bank transfer to Trust A, an institution in the 50% deduction category.
| Item | Amount |
|---|---|
| Donation | Rs 50,000 |
| Deduction at 50% | Rs 25,000 |
| Tax saved at 30% slab | Rs 7,500 |
| Add 4% health and education cess | Rs 300 |
| Total tax saved | Rs 7,800 |
The arithmetic above assumes the donation falls within any qualifying limit that section 80G applies to that category of institution. You can test the full effect on your liability with Oquilia's old regime income tax calculator or compare both regimes in the old vs new regime calculator. If Ravi had opted for the new regime, the deduction would be Rs 0, because section 80G is an old-regime deduction only.
Common Mistakes
1. Treating condonation as approval. Paragraph 5 of Circular 6/2026 states plainly that nothing in it confers any automatic entitlement to approval under section 80G(5) of the 1961 Act or section 133(1)(b) of the 2025 Act. An institution that tells donors in November 2026 that its 80G status is "restored" before the Commissioner's order is overstating the position.
2. Assuming every late filing is covered. The window is fixed at 1 October 2025 to 31 March 2026. A Form 10AB filed on 1 April 2026 or later sits outside paragraph 3, as Case C above shows.
3. Reading paragraph 4 too widely. The deemed condonation applies only where the rejection was "solely" on the ground that Form 10AB was furnished beyond 30 September 2025. A rejection order that also cites defects in documents, objects or activities is not covered by paragraph 4.
4. Ignoring the 31 December 2026 deadline. The circular directs the Commissioner to pass an order on or before 31 December 2026. Institutions should keep their e-filing account active and answer any notice on the Income Tax e-filing portal promptly, because a delayed response in the final weeks of December 2026 leaves little room.
5. Donors claiming 80G in the new regime. Section 80G is available only in the old regime. A donor who files an ITR under the new regime and claims an 80G deduction will see it disallowed at processing. Use the income tax calculator to check which regime gives the lower liability for FY 2025-26 before relying on a donation to cut tax.
6. Confusing a deduction with an exemption. An 80G donation reduces taxable income; it is a deduction, not a tax exemption of the donor's income. On a Rs 50,000 donation to a 50% institution, only Rs 25,000 comes off taxable income, as the worked example shows.
FAQ
What is CBDT Circular No. 6/2026 about?
Circular No. 6/2026 (F. No. 300176/3/2026-ITA-I) condones the delay in filing Form No. 10AB for renewal of section 80G(5) approval. It covers funds and institutions whose approval was expiring on 31 March 2026 and which filed Form 10AB electronically between 1 October 2025 and 31 March 2026, after the 30 September 2025 due date.
Under which power did CBDT issue the circular?
CBDT used section 119(2)(b) of the Income-tax Act, 1961, read with section 536(2) of the Income-tax Act, 2025. Section 119(2)(b) allows the Board to authorise admission of a late application to avoid genuine hardship.
My trust's Form 10AB was already rejected for being late. What happens now?
Under paragraph 4 of the circular, if the application was filed between 1 October 2025 and 31 March 2026 and was rejected solely because it was filed after 30 September 2025, the delay is deemed condoned. The Commissioner must decide it afresh on merits by 31 December 2026.
Does the circular guarantee 80G approval?
No. Paragraph 5 says nothing in the circular confers any automatic entitlement to approval under section 80G(5) of the 1961 Act or section 133(1)(b) of the 2025 Act. The Commissioner examines each application on merits.
By when must the Commissioner decide?
The jurisdictional Principal Commissioner or Commissioner of Income-tax must pass an order on or before 31 December 2026, under both paragraph 3 and paragraph 4 of the circular.
Can I claim an 80G deduction under the new tax regime?
No. Section 80G is available only under the old tax regime. Under the old regime, the deduction is 50% or 100% of the eligible donation depending on the institution, so a Rs 50,000 donation to a 50% institution gives a Rs 25,000 deduction.
Where can I read the circular?
The full circular is published on the Income Tax Department website at incometax.gov.in, under the July 2026 uploads, as Circular-No-06-2026.pdf. The parent statute, the Income-tax Act, 1961, is available on India Code.
This article explains CBDT Circular No. 6/2026 as published on incometax.gov.in. It is not tax advice; trusts should confirm the status of their own Form 10AB application on the e-filing portal before 31 December 2026.
Sources & Citations
- Circular No. 6/2026: Condonation of delay in filing Form No. 10AB under section 80G(5) — Income Tax Department
- Income Tax e-filing portal — Income Tax Department
- India Code: Income-tax Act, 1961 — India Code