
ITAT Kolkata allows co-operative society 80P deduction on bank deposit interest
The ITAT Kolkata bench held that a Hooghly co-operative society can claim the Section 80P deduction on interest from deposits made out of its own business surplus.
Key points
- The Income Tax Appellate Tribunal, Kolkata, on 29 October 2026 allowed three appeals of a Hooghly co-operative marketing society.
- The tribunal directed deletion of a Rs 22,82,839 addition, holding interest on deposits from the society's own surplus qualifies for 80P.
- It also quashed the 2016-17 assessment because an officer without jurisdiction under a CBDT instruction made it.
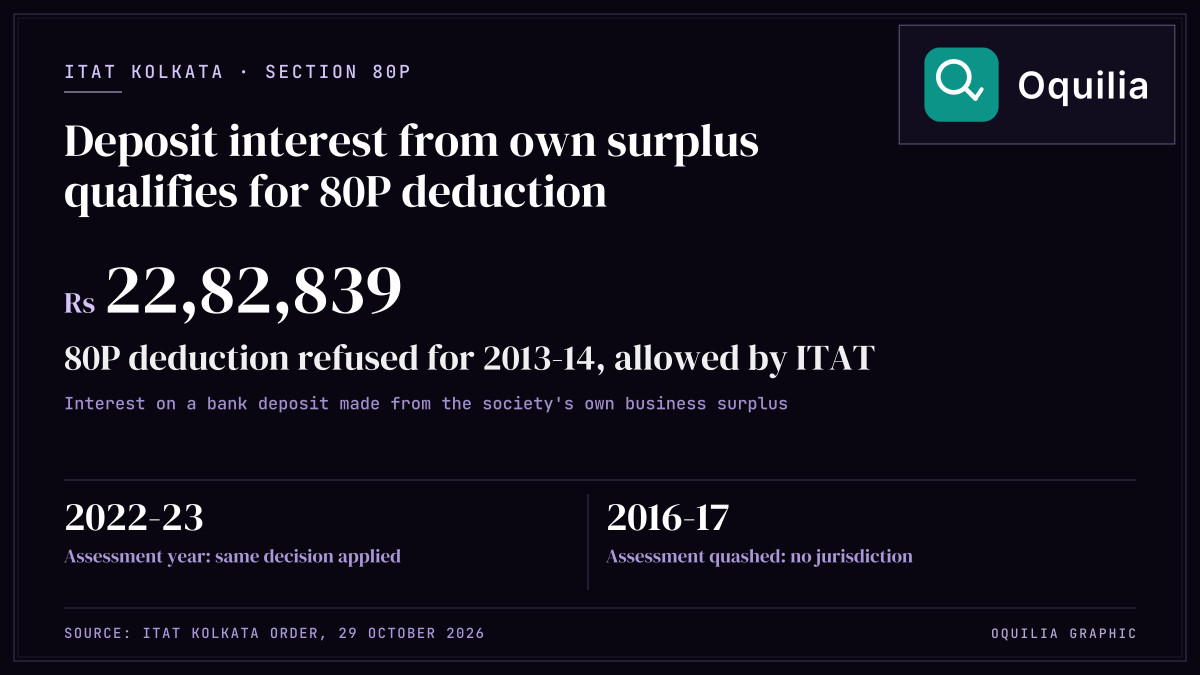
The Kolkata bench of the Income Tax Appellate Tribunal (ITAT) on 29 October 2026 held that a primary agricultural co-operative society can claim the Section 80P deduction on interest earned from bank deposits made out of its own business surplus. It allowed all three appeals of Singur Thana L.S.P.A Co-operative Marketing Society Ltd. in Hooghly, West Bengal, and also quashed one assessment as made by an officer without jurisdiction.
What Happened
According to the order, for assessment year 2013-14 the tax officer refused the society a deduction of Rs 22,82,839 under Section 80P, which gives co-operative societies a tax deduction on income from specified activities. The officer said the interest from the society's deposit with Allahabad Bank's Singur branch was not attributable to its business of giving credit to members or marketing their produce, and treated it as "other income", relying on a Supreme Court ruling. The Commissioner of Income Tax (Appeals) agreed.
The tribunal held that the deposit was made long ago out of the society's own surplus funds, generated from the business for which it was set up. The interest is therefore covered by Section 80P(2)(a)(i), it held, and the Supreme Court ruling relied on by the officer is different because, there, the deposits were amounts payable to members. It directed the officer to delete the addition, and applied the same decision to assessment year 2022-23.
For assessment year 2016-17, the society had declared nil income, but the notice and assessment were issued by an assistant commissioner-level officer. Under a 2011 instruction of the Central Board of Direct Taxes, such a case lies with an income tax officer, the tribunal noted. It held the notice and assessment invalid and quashed the assessment.
What It Means
For primary agricultural credit and marketing societies, the order means interest on bank deposits made from their own business surplus can qualify for the Section 80P deduction, as long as the money is not funds owed to members. It also shows that an assessment made by an officer outside the income limits set by the Board for assigning cases can be quashed. The ruling is the tribunal's decision in this society's case.
Source: ITAT order
Sources & Citations
- ITAT order — Income Tax Appellate Tribunal