
ITAT Delhi quashes retrospective cancellation of school society's charity registration
The Income Tax Appellate Tribunal in Delhi quashed orders cancelling a school society's charitable registration from AY 2019-20 and directed renewal of its Section 12A registration and 80G approval.
Key points
- The Income Tax Appellate Tribunal's Delhi bench on 18 November 2026 allowed two appeals by Delhi Vocational School Society.
- It quashed the tax department's orders of 17 and 27 March 2026 cancelling the society's registration and rejecting its 80G renewal.
- The tribunal held the officer exceeded his jurisdiction and directed renewal of registration and 80G approval forthwith.
The Income Tax Appellate Tribunal (ITAT) in Delhi on 18 November 2026 quashed orders that had cancelled the charitable registration of Delhi Vocational School Society with retrospective effect and rejected renewal of its approval under Section 80G. The tribunal directed the tax department to renew both.
What Happened
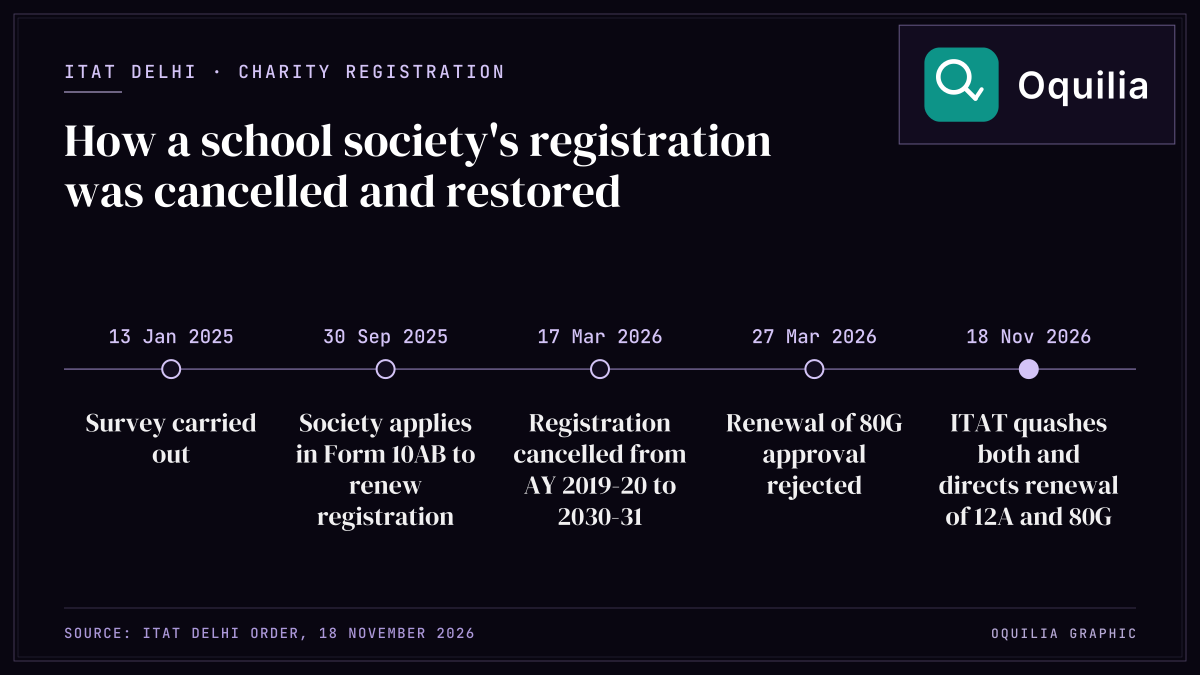
The society runs a school in Kailash Colony, New Delhi, and held registration under Section 12A and approval under Section 80G of the Income-tax Act for assessment years 2022-23 to 2026-27. On 30 September 2025 it applied in Form 10AB to renew its registration for five years from assessment year 2027-28.
After a survey on 13 January 2025, the Principal Commissioner of Income Tax (Central), Delhi, by an order of 17 March 2026, cancelled the registration from assessment year 2019-20 to 2030-31, and on 27 March 2026 rejected the 80G renewal. According to the tribunal's order, the department treated advances to certain suppliers and contractors as bogus expenditure and diversion of charitable funds, and treated transport receipts as business income without separate accounts. The society said its educational activities were genuine and that transport for students was part of running the school.
The tribunal held that at the registration or renewal stage the authority may examine only whether the objects are charitable and the activities genuine. Questions about individual expenses or purchases belong to the Assessing Officer in assessment. Following earlier rulings of its benches, it held that the concept of specified violations came into force on 1 April 2022 and cannot be used to cancel registration retrospectively. It found the order was in excess of jurisdiction and directed renewal of registration and grant of 80G approval forthwith.
What It Means
Registration under Section 12A lets a trust or society claim income-tax exemption, and 80G approval lets its donors claim a deduction for donations. The ruling adds to a line of tribunal decisions holding that the tax department cannot use the renewal process to cancel registration for past years on grounds that belong in assessment.
Source: ITAT order
Sources & Citations
- ITAT order — Income Tax Appellate Tribunal