

India's capital gains tax framework underwent its most significant revision in a decade through Budget 2024, and the rules continue to apply for FY 2026-27 (AY 2027-28) with no change to these rates in Budget 2026, which did propose taxing share buyback proceeds as capital gains for all shareholders. The new structure simplifies holding periods, standardises rates across asset classes, and removes the benefit of indexation for most assets. Whether you trade equities, hold debt mutual funds, or are selling property, understanding the current rules is essential for tax-efficient investing.
Equity and Equity Mutual Funds
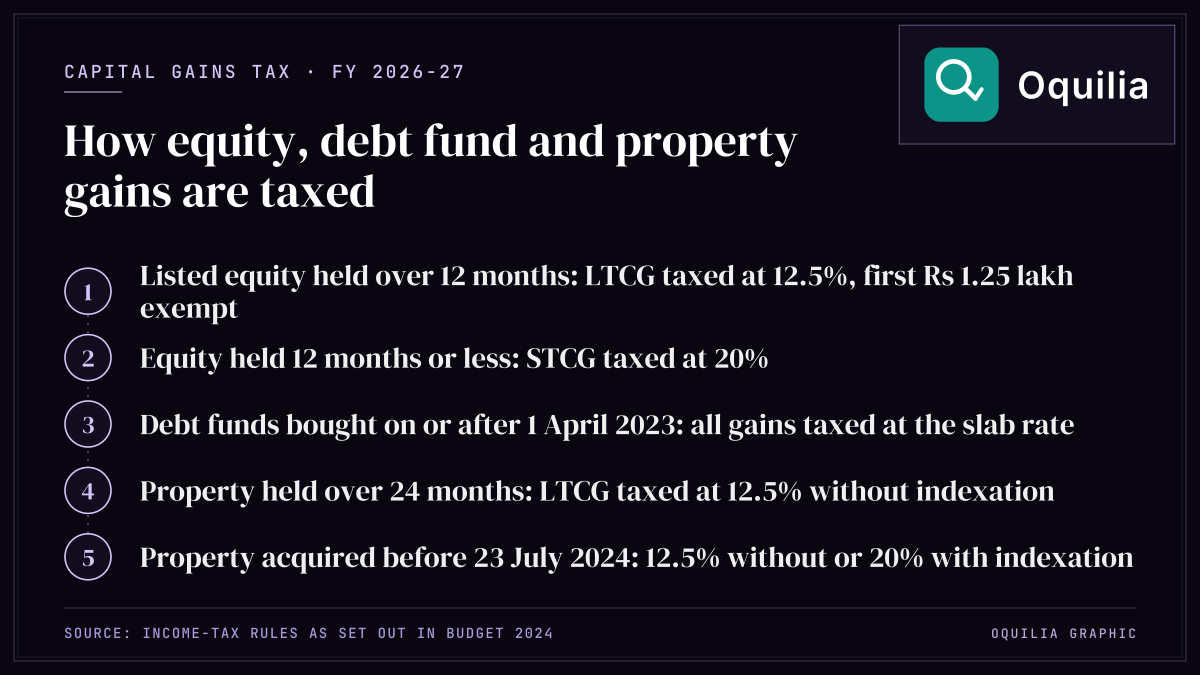
Listed equity shares and equity-oriented mutual fund units held for more than 12 months qualify as long-term capital assets. Long-Term Capital Gains (LTCG) are taxed at a flat rate of 12.5% without indexation benefit. The first Rs 1.25 lakh of LTCG in a financial year is exempt under Section 112A. Short-Term Capital Gains (STCG) on equity, where the holding period is 12 months or less, are taxed at 20%.
This means an investor who books Rs 3 lakh in LTCG from equity in FY 2026-27 will pay tax on Rs 1.75 lakh at 12.5%, resulting in a tax liability of Rs 21,875 plus applicable cess. The Rs 1.25 lakh exemption is per taxpayer per financial year and covers gains from all listed equity and equity mutual fund transactions combined. Investors should plan redemptions strategically to utilise the full exemption each year rather than booking large gains in a single year.
Debt Mutual Funds and Bonds
Debt mutual funds, meaning schemes that invest more than 65% of their money in debt and money market instruments, are covered by Section 50AA. For units acquired on or after 1 April 2023, all gains regardless of holding period are taxed at the investor's applicable slab rate. The earlier distinction between STCG and LTCG for debt funds has been eliminated. There is no indexation benefit available for these instruments. Gold funds, international equity funds and fund-of-funds that are not mainly in debt have been outside this rule since 1 April 2025: their gains are long-term after 24 months (12 months for listed units) and taxed at 12.5% without indexation.
For investors in the 30% tax bracket, this effectively means a 31.2% (with cess) tax on all debt mutual fund gains. This has made direct investment in tax-free bonds, PPF, and certain sovereign gold bonds relatively more attractive for the fixed-income portion of portfolios. Debt fund investors should consider holding investments in lower-income years or exploring insurance-wrapped fixed-income products where applicable.
Real Estate and Property
Real estate held for more than 24 months is classified as a long-term capital asset. The LTCG rate is 12.5% without indexation, replacing the earlier 20% with indexation benefit. For land or buildings acquired before 23 July 2024, a resident individual or HUF has the option to compute tax at either 12.5% without indexation or 20% with indexation (using the Cost Inflation Index for the year of sale), and choose whichever results in lower tax. CBDT has clarified that this grandfathering provision applies only to transfers of assets held before the cut-off date.
The removal of indexation benefits disproportionately affects long-term property holders who purchased at significantly lower costs. A property bought in 2005 for Rs 20 lakh and sold in early 2026 (FY 2025-26) for Rs 1.2 crore would have an indexed cost of approximately Rs 64.3 lakh under the old rules (CII 2005-06: 117, CII 2025-26: 376), resulting in LTCG of Rs 55.7 lakh taxed at 20% equalling Rs 11.1 lakh. Under the new rules without indexation, the gain is Rs 1 crore taxed at 12.5% equalling Rs 12.5 lakh. The grandfathering option lets the taxpayer choose the lower amount.
Key Planning Takeaways for FY 2026-27
First, harvest equity LTCG up to Rs 1.25 lakh each year by selling and repurchasing (after considering exit loads and transaction costs) to reset your cost base. Second, for debt investments, consider holding period and your tax slab before choosing between mutual funds and direct bonds. Third, for property transactions, compute tax under both the old and new methods if the asset was acquired before 23 July 2024. Fourth, maintain meticulous records of purchase dates and costs since the holding period and cost base determine both the applicable rate and the availability of grandfathering benefits.
Source
Finance Act 2024, Finance Act 2026, CBDT Notifications