

The Union Budget 2026, presented on 1 February 2026 by Finance Minister Nirmala Sitharaman, left personal income tax slabs and rates unchanged, so the overhaul of the new tax regime made in Budget 2025 carries into FY 2026-27. The nil-tax threshold is Rs 12 lakh (Rs 12.75 lakh for salaried individuals after the standard deduction), with the restructured slab rates under Section 115BAC. The old regime, with its traditional slabs, remains available but unchanged. For FY 2026-27 (AY 2027-28), taxpayers must evaluate both regimes carefully before making a choice.
The Revised New Regime Slabs for FY 2026-27
Under the revised new regime, income up to Rs 4 lakh attracts nil tax. The next slab, from Rs 4 lakh to Rs 8 lakh, is taxed at 5%. Income between Rs 8 lakh and Rs 12 lakh is taxed at 10%. From Rs 12 lakh to Rs 16 lakh the rate is 15%, from Rs 16 lakh to Rs 20 lakh it is 20%, from Rs 20 lakh to Rs 24 lakh it is 25%, and income above Rs 24 lakh is taxed at 30%. A rebate under Section 87A ensures that individuals with total income up to Rs 12 lakh pay zero tax under the new regime.
The old regime retains the familiar structure: nil tax up to Rs 2.5 lakh (Rs 3 lakh for senior citizens), 5% from Rs 2.5 lakh to Rs 5 lakh, 20% from Rs 5 lakh to Rs 10 lakh, and 30% above Rs 10 lakh. Section 87A rebate in the old regime applies only up to Rs 5 lakh of total income.
Deductions: Where the Old Regime Still Wins
The new regime allows only the standard deduction of Rs 75,000 and employer NPS contribution under Section 80CCD(2). All other deductions including Section 80C (Rs 1.5 lakh), Section 80D (health insurance), HRA exemption, home loan interest under Section 24(b), and LTA are unavailable. The old regime permits the full stack of deductions and exemptions, which can total Rs 4-5 lakh for an employee with a home loan, health insurance, and NPS contributions.
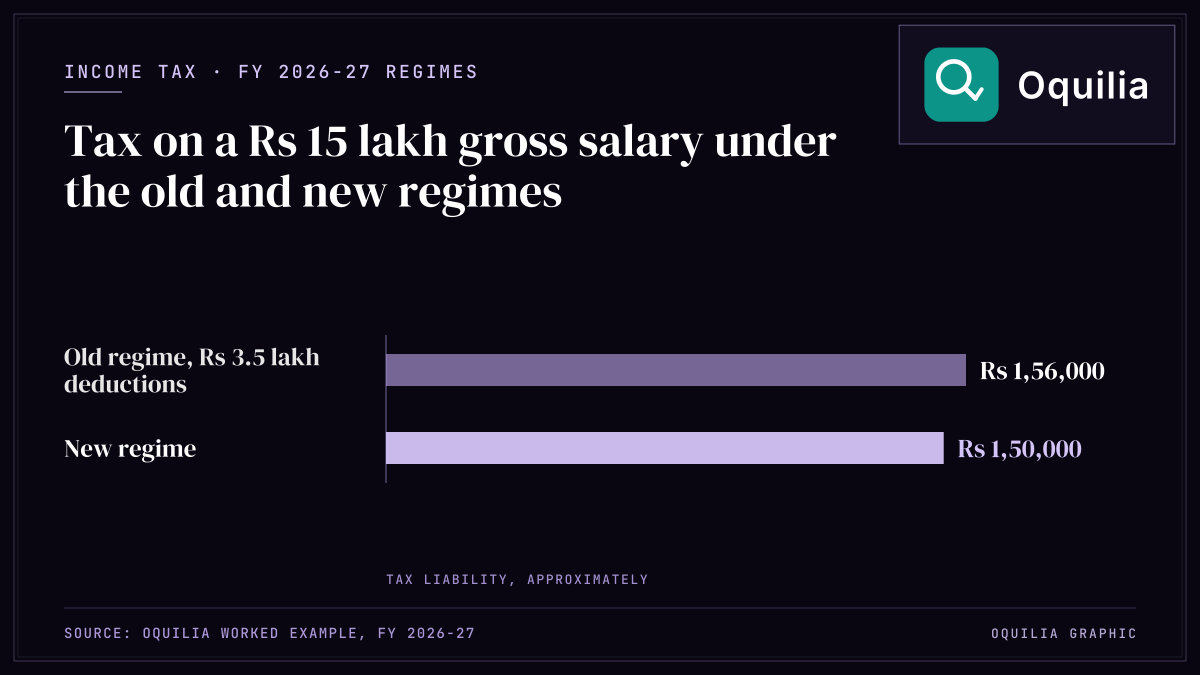
For a salaried individual earning Rs 15 lakh gross with Rs 3.5 lakh in deductions under the old regime, the tax liability works out to approximately Rs 1,63,800 under the old regime versus Rs 97,500 under the new regime (both including cess). At this income level the new regime wins by a wide margin. At Rs 20 lakh gross with Rs 4.5 lakh in deductions, the new regime still saves about Rs 96,000 (Rs 1,92,400 against Rs 2,88,600); the old regime comes out ahead at that salary only when deductions exceed roughly Rs 7.6 lakh.
Who Should Choose Which Regime
The new regime is generally advantageous for individuals with annual income below Rs 12 lakh, those who do not have a home loan, and younger professionals who have not yet built a significant deduction portfolio. The old regime continues to favour individuals with home loan interest exceeding Rs 2 lakh, those making full use of 80C, 80D, and 80CCD(1B) deductions, and salaried employees with substantial HRA claims in metro cities.
CBDT clarified in Circular No. 4/2023 that salaried employees must tell their employer which regime they intend to use each year for correct TDS deduction. The regime can be switched at the time of ITR filing, but any excess or shortfall in TDS will need to be adjusted. Self-employed individuals and professionals with business income have less freedom: they opt out of the new regime by filing Form 10-IEA, and can switch back to it only once.
Practical Decision Framework
To make the right choice, list all deductions and exemptions you are eligible for under the old regime. On the current slabs the old regime saves more tax only when deductions are large: roughly Rs 5.9 lakh or more at Rs 15 lakh gross, Rs 7.6 lakh at Rs 20 lakh and Rs 8.4 lakh at Rs 24 lakh. Below Rs 12 lakh, the new regime is almost always better due to the full rebate. Above Rs 24 lakh, the calculation depends heavily on whether you have a home loan and NPS investments. Use the Oquilia Old vs New Regime Calculator to compare your exact liability under both regimes before making a decision.
Source
Finance Act 2025, Finance Act 2026, Income Tax Department, CBDT Circular No. 4/2023