
NCLT admits Richesm Healthcare into insolvency on Kotak Mahindra Bank's Rs 18.92 crore claim
The NCLT's Allahabad bench has admitted Noida-based Richesm Healthcare Limited into insolvency on a petition by Kotak Mahindra Bank over a default of Rs 18.92 crore.
Key points
- The NCLT's Allahabad bench admitted Richesm Healthcare Limited into insolvency on Kotak Mahindra Bank's petition on 26 October 2026.
- The bank put the default at Rs 18,92,17,474.96 on loans of Rs 20 crore sanctioned in February 2025, with the default dated 7 July 2025.
- The interim resolution professional must issue a public announcement calling for claims; the order may be appealed to the NCLAT.
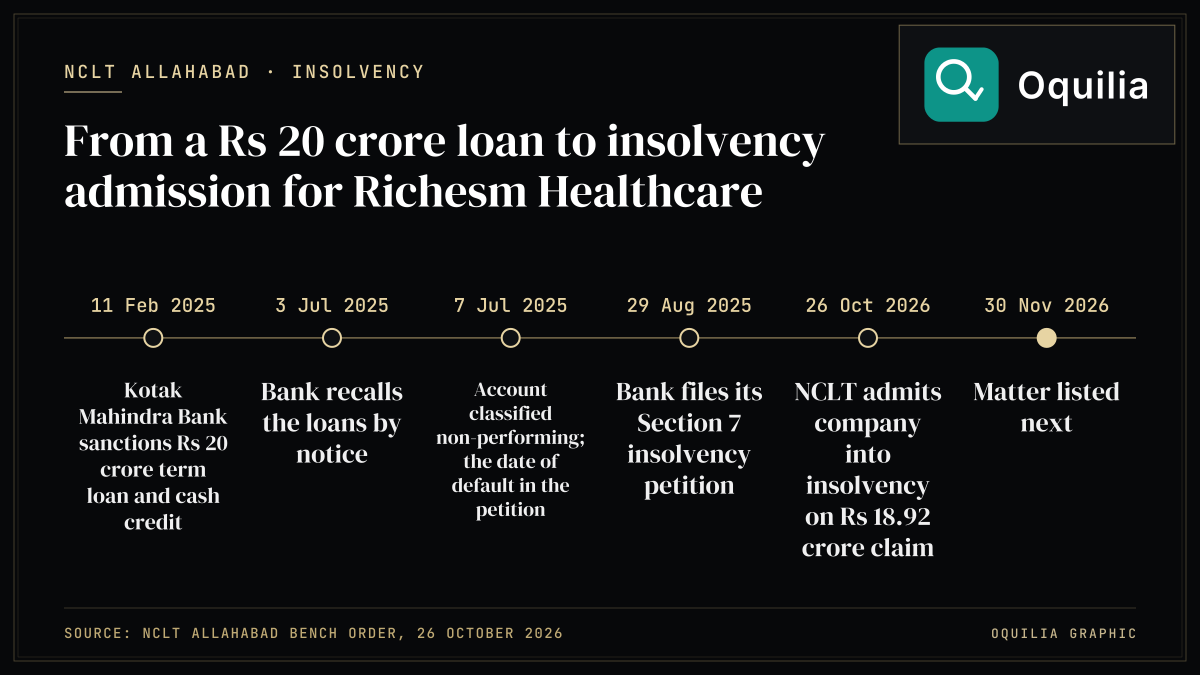
The National Company Law Tribunal (NCLT), Allahabad bench, has admitted Noida-based Richesm Healthcare Limited into the corporate insolvency resolution process on a petition by Kotak Mahindra Bank. The order, pronounced on 26 October 2026, records the bank's claim of a default of Rs 18,92,17,474.96, made up of Rs 18,35,88,444.58 in principal and Rs 56,29,030.38 in interest.
What Happened
According to the order, the bank sanctioned the company a term loan of Rs 12 crore and a cash credit limit of Rs 8 crore, together Rs 20 crore, by a letter dated 11 February 2025. The bank said the company failed to repay, recalled the loans by a notice dated 3 July 2025 and classified the account as a non-performing asset on 7 July 2025, the date of default given in the petition, which was filed on 29 August 2025.
The order records that in a letter of 9 July 2025, sent through its counsel, the company said it could not pay instalments on time due to "unavoidable circumstances" and would repay within six months. The bank replied that no repayment plan or proof of financial capacity had been offered.
The company argued that the petition could not proceed because the bank had already filed a personal insolvency petition against its suspended director as guarantor of the loans, which triggered an interim moratorium. The tribunal held that this moratorium covers only the guarantor's debts and does not bar insolvency proceedings against the company itself. It found the conditions under Section 7 of the Insolvency and Bankruptcy Code satisfied.
What It Means
An interim resolution professional appointed by the tribunal now runs the company and must make a public announcement immediately, calling for claims. Creditors should file their claims as that announcement directs. A moratorium bars suits, recovery and the sale of the company's assets during the process, and the bank must deposit Rs 1 lakh for initial expenses. The matter is listed next on 30 November 2026.
Admission into insolvency is not a finding of fraud or mismanagement. The NCLT's order may be appealed to the National Company Law Appellate Tribunal (NCLAT).
Source: NCLT order
Sources & Citations
- NCLT order — National Company Law Tribunal