

The Ministry of Finance has announced small savings rates for the April-June 2026 quarter (Q1 FY27), keeping the Sukanya Samriddhi Yojana (SSY) interest rate unchanged at 8.2% per annum, compounded annually. That keeps SSY level with the Senior Citizens Savings Scheme (also 8.2%, with interest paid out every quarter) at the top of the government small savings table, ahead of the Public Provident Fund (7.1%). The retention comes amidst broader market expectations of rate cuts following the RBI's accommodative stance.
SSY: How It Works
Sukanya Samriddhi Yojana, launched in January 2015 under the Beti Bachao, Beti Padhao initiative, is a government-backed savings scheme exclusively for the girl child. A parent or guardian can open an account for a girl below age 10, with a minimum annual deposit of Rs 250 and a maximum of Rs 1.5 lakh. Deposits must be made for the first 15 years, after which the account continues to earn interest until maturity (21 years from account opening or on the girl's marriage after age 18, whichever is earlier). The entire accumulation enjoys EEE (Exempt-Exempt-Exempt) tax treatment under Section 80C for contributions, and both interest and maturity proceeds are fully tax-free.
SSY vs Other Options: A Comparative Analysis
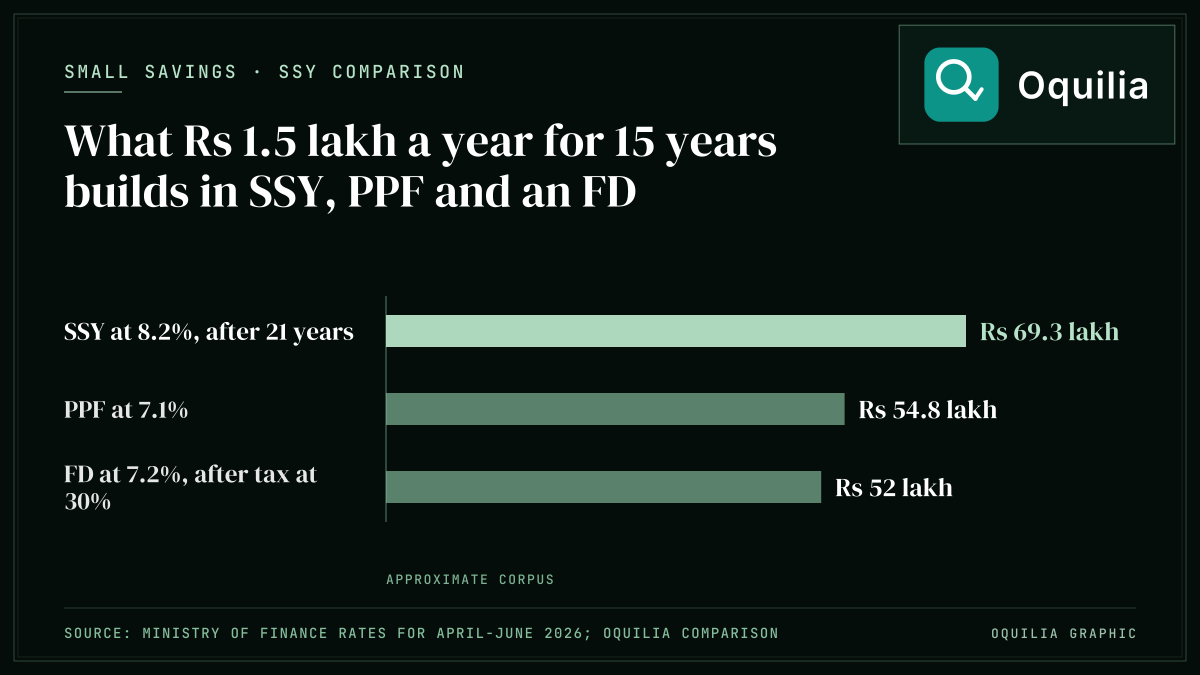
For a parent investing Rs 1.5 lakh per year for 15 years, SSY at 8.2% yields approximately Rs 69.3 lakh at the end of 21 years on a total investment of Rs 22.5 lakh. Comparing this with alternatives: PPF at 7.1% for the same investment pattern yields approximately Rs 54.8 lakh (15 years contribution, extendable in 5-year blocks). A large-cap equity mutual fund SIP of Rs 12,500 per month for 21 years at a historical average return of 12% would yield approximately Rs 1.27 crore, but with market risk and capital gains tax implications. A fixed deposit at 7.2% (current senior citizen FD rate) yields approximately Rs 52 lakh after tax at the 30% slab.
The Case for SSY
SSY's core advantage is risk-free, guaranteed returns with sovereign backing and complete tax exemption. For conservative families, especially in Tier 2 and Tier 3 cities where equity market participation is low, SSY remains the optimal choice. The 8.2% rate, which is benchmarked to the 10-year government bond yield plus a 75-basis-point spread, is generous by global standards. No comparable risk-free instrument in India offers this combination of rate and tax benefit.
The Case Against Relying Solely on SSY
However, financial planners increasingly recommend a blended approach. SSY's lock-in of 21 years and the annual cap of Rs 1.5 lakh mean it cannot be the sole vehicle for goals like higher education (which may require Rs 30-50 lakh by 2040 for a premier institution). A parent who invests Rs 1.5 lakh in SSY and an additional Rs 1 lakh per year in a balanced advantage mutual fund creates both a guaranteed base and a growth component. Partial withdrawal of up to 50% of the balance is permitted after the girl turns 18, providing flexibility for education expenses.
Should You Open an SSY Account Now?
If you have a daughter under 10 and have not yet opened an SSY account, there is no reason to delay. The rate is not locked in, though: the government resets it every quarter, and each new rate applies to the whole balance, so a cut in a future quarter (possible given the softening interest rate environment) would also lower the return on money already deposited. The account can be opened at any India Post office or authorised bank branch with minimal documentation (birth certificate, parent ID proof, and address proof).
Source
Ministry of Finance, Small Savings Rates Notification Q1 FY2026-27