

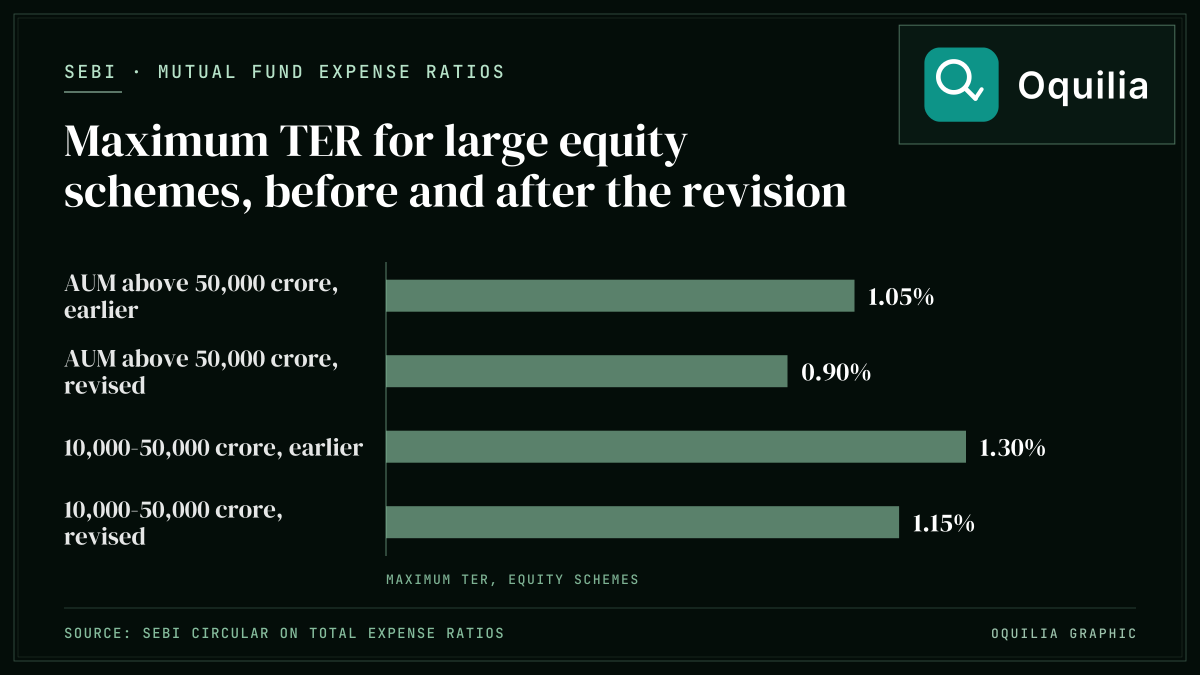
The Securities and Exchange Board of India (SEBI) has notified the SEBI (Mutual Funds) Regulations, 2026, which replace the 1996 regulations from 1 April 2026 and recast the expense limits that fund houses can charge investors. The revision, approved by the SEBI Board on 17 December 2025, follows SEBI's ongoing effort to make mutual fund investing more cost-effective, building on the landmark TER reduction of 2018.
Key Changes in the New TER Structure
The limits are renamed the Base Expense Ratio (BER) and now exclude statutory levies such as GST, STT and stamp duty, which are charged on actuals; the total expense ratio becomes the BER plus brokerage and levies. For open-ended equity schemes, the BER on the first 500 crore of assets is 2.10% (against a TER limit of 2.25% that included levies), falling slab by slab to 0.95% on assets above 50,000 crore (against 1.05%). In between, the 10,000-15,000 crore slab moves from 1.45% to 1.35% and the 45,000-50,000 crore slab from 1.10% to 1.00%. Debt and other non-equity schemes move from 2.00% to 1.85% on the first 500 crore and from 0.80% to 0.70% above 50,000 crore. Brokerage caps net of levies fall to 6 basis points for cash-market trades and 2 basis points for derivatives, and the additional 5 basis points allowed for schemes with exit loads has been removed. The industry's assets stood at about 80 lakh crore in December 2025 (AMFI).
For index funds and ETFs, the cap moves from 1.00% (including levies) to 0.90% (excluding levies).
Impact on Your Returns
Because levies now sit outside the cap, the fall in what investors actually pay is smaller than the headline cut for many schemes. Even so, small differences compound over long horizons. On a 1 lakh monthly SIP running for 20 years at an assumed 12% gross return, an annual cost lower by 0.15 percentage points adds roughly 20 lakh to the corpus at maturity (about 9.99 crore against 9.79 crore). For larger portfolios, the absolute savings are proportionally greater.
What Investors Should Do
Review your existing mutual fund portfolio and check whether you are in direct plans. The TER difference between regular and direct plans ranges from 0.5% to 1.0%, which dwarfs the slab revision. If you are still investing through regular plans via distributors, the switch to direct plans remains the single most impactful cost reduction available to you.
For new investors, this revision makes systematic investing through mutual funds even more attractive compared to traditional instruments like FDs and endowment policies, where embedded costs are often opaque and significantly higher.
Source
SEBI (Mutual Funds) Regulations, 2026; SEBI Board meeting, PR No. 84/2025, 17 December 2025