

If you have been holding cash in a savings account while waiting for the "right time" to book a fixed deposit, that window is closing fast. Following the RBI's 125 basis points of repo rate cuts through 2025, banks have been trimming FD rates — and the cuts are expected to deepen over the next two quarters.
How Much Have FD Rates Already Fallen?
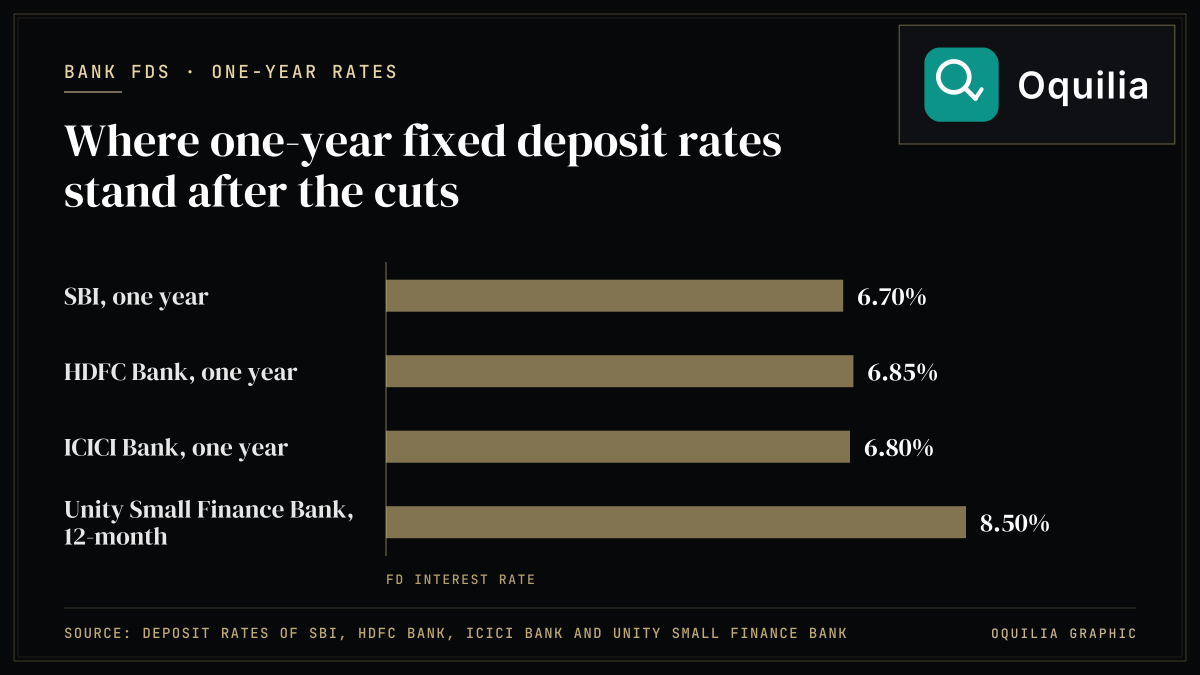
SBI's one-year FD rate has been 6.25% since July 2025, and in December 2025 it trimmed its two-to-three-year rate to 6.40% from 6.45%. Its popular five-year FD, which plays into the 80C tax-saving category, offers 6.05%. HDFC Bank's one-year deposit rate has dropped to 6.85% from 7.10% in October 2025, a 25 bps decline. ICICI Bank has followed a similar trajectory, with its one-year rate now at 6.80%.
Small finance banks, which had been offering headline rates of 8.5-9.0% during the tight liquidity conditions of 2025, have also started moderating. Unity Small Finance Bank, for example, reduced its 12-month rate from 9.00% to 8.50% effective March 2026. AU Small Finance Bank dropped to 7.75% from 8.10%.
Why the Decline Will Continue
The mechanics are straightforward. When the repo rate falls, banks' cost of borrowing from the RBI decreases. To maintain their net interest margins, banks reduce both lending and deposit rates. With the repo rate now at 5.25% and further cuts possible if inflation remains contained, the direction for deposit rates is unambiguously downward. The weighted average domestic term deposit rate on outstanding deposits, as tracked by the RBI, has already declined from 6.78% in October 2025 to 6.62% in February 2026.
Strategy for Conservative Investors
The immediate action for risk-averse investors is to lock in current rates at the longest comfortable tenure. A five-year FD booked today at 6.50-7.00% will retain that rate for the full term, regardless of how far the repo rate falls. Senior citizens, who receive an additional 50 bps premium at most banks, should be particularly proactive. A 7.00-7.50% FD locked in now could look extremely attractive 12 months from now if headline rates fall to 6.00-6.50%.
Laddering remains a sound approach. Instead of placing the entire corpus in one FD, split it across one-year, two-year, three-year, and five-year tenures. This ensures some portion matures regularly and can be reinvested if rates improve, while the longer-dated tranches lock in today's relatively higher yields.
Investors comfortable with slightly higher risk should evaluate debt mutual funds in the short-duration and corporate bond categories. These funds benefit from capital appreciation when interest rates fall, potentially delivering 7.5-8.5% post-tax returns in a declining rate cycle — meaningfully better than what FDs will offer after tax.
Tax Angle to Consider
FD interest is fully taxable at the investor's marginal income tax slab. For someone in the 30% tax bracket, a 6.70% FD yields only 4.69% post-tax. Under the new tax regime, where the basic exemption is Rs 4 lakh, senior citizens in the lower brackets benefit more. Using the FD calculator to compare pre-tax and post-tax returns across different scenarios is essential before committing funds.
Source
SBI FD rate card March 2026; HDFC Bank deposit rate circular; RBI data on term deposits