

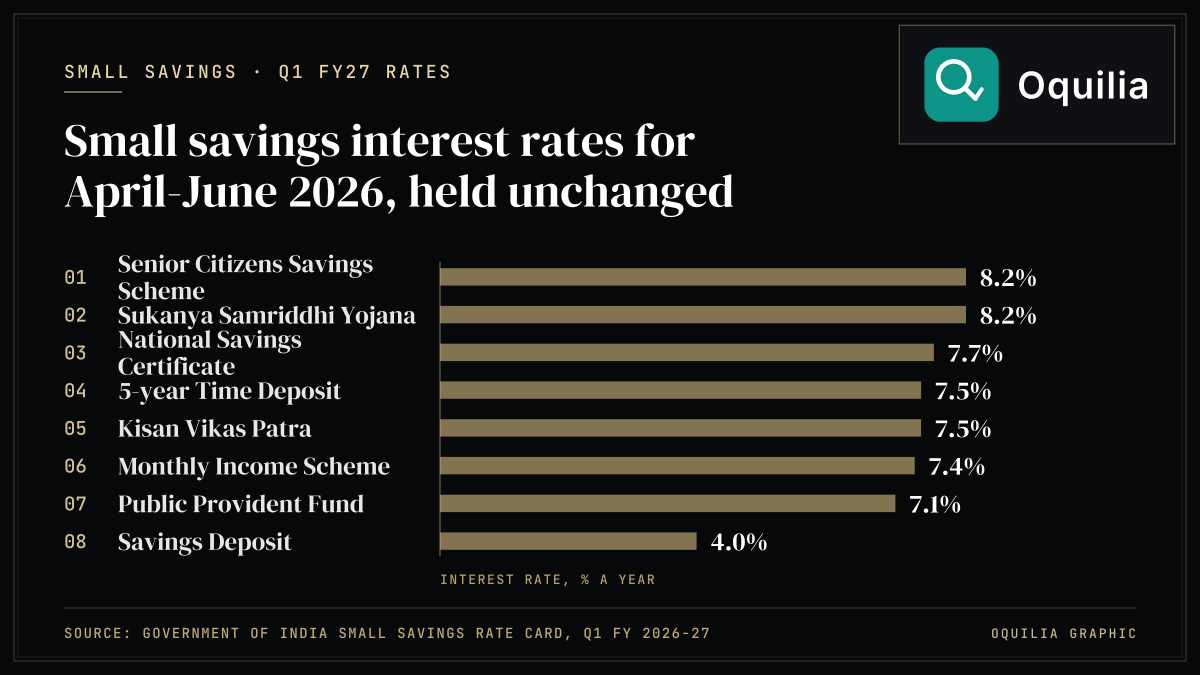
The Government of India has decided to keep small savings scheme interest rates unchanged for the first quarter of FY 2026-27 (April-June 2026), the Finance Ministry notified on 30 March 2026. The Public Provident Fund (PPF) remains at 7.1%, National Savings Certificate (NSC) at 7.7%, and the Senior Citizens Savings Scheme (SCSS) at 8.2%. The Sukanya Samriddhi Yojana (SSY) rate also stays at 8.2%.
Rate Card for Q1 FY27
The full rate card: Savings Deposit at 4.0%, 1-year Time Deposit at 6.9%, 2-year at 7.0%, 3-year at 7.1%, 5-year at 7.5%, 5-year Recurring Deposit at 6.7%, Monthly Income Scheme at 7.4%, NSC at 7.7%, PPF at 7.1%, Kisan Vikas Patra at 7.5% (matures in 115 months), SCSS at 8.2%, and SSY at 8.2%. These rates have been unchanged since the January-March 2024 quarter.
How Small Savings Compare with Market Alternatives
PPF at 7.1% with tax-free status translates to a pre-tax equivalent of approximately 10.1% for investors in the 30% tax bracket. This makes PPF competitive with most post-tax returns from equity mutual funds over shorter time horizons and significantly better than taxable FDs. However, the 15-year lock-in (with partial withdrawal from year 7) remains a constraint.
SCSS at 8.2% remains the best fixed-income option for senior citizens, offering quarterly payouts and capital safety. The maximum investment is Rs 30 lakh per individual across all SCSS accounts, raised from Rs 15 lakh in April 2023, so a retired couple with an account each can deploy up to Rs 60 lakh and earn approximately Rs 4,92,000 a year in interest. For senior citizens, a bank or post office deducts TDS only when interest from that payer exceeds Rs 1 lakh in a year (the threshold since April 2025).
Should You Invest in Small Savings?
Small savings schemes remain essential building blocks for conservative investors and retirees. PPF should be part of every salaried individual's portfolio as a tax-free debt component. SSY is unmatched for parents saving for a daughter's future. SCSS is the default post-retirement instrument. The key limitation is liquidity; if you may need the funds before the lock-in period ends, bank FDs or liquid mutual funds offer better access despite slightly lower post-tax returns.
Source
Ministry of Finance (Department of Economic Affairs), Office Memorandum of 30 March 2026