

The IRDAI released its Annual Report for 2024-25 on 30 December 2025, with the industry's death-claim data for life insurance companies. For term insurance buyers, this data is critical because claim settlement is the only metric that ultimately matters. A term policy with a low premium but a poor claims record is worse than worthless. Here is what the data reveals.
Overall Industry Performance
Life insurers received 10,34,455 individual death claims in FY25 and paid 10,11,880 of them, or 97.82% by number, down from 98.26% (9,82,615 of 10,00,045 claims) in FY24. They repudiated 10,494 claims (1.01%) under Section 45 of the Insurance Act, rejected 6,839 (0.66%) under policy terms, and had 4,999 (0.48%) pending at the end of the year. By amount, insurers paid Rs 33,697 crore of the Rs 34,995 crore claimed (96.29%); repudiated claims accounted for Rs 958 crore. In group business, 99.68% of claims were paid by number.
Key Findings for Term Insurance
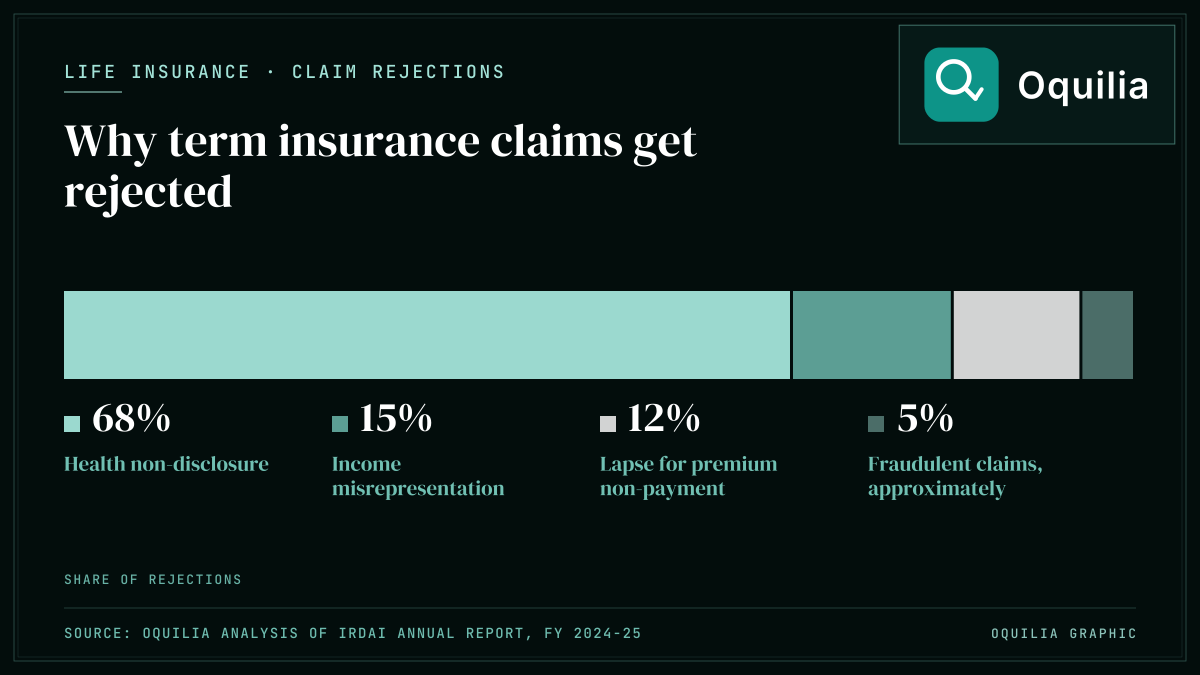
The annual report gives industry totals only. It does not split death claims by insurer or by product, so it does not show a separate settlement ratio for pure term policies or for any single company. Insurer-wise figures are in each life insurer's own public disclosures. The gap between the ratio by number (97.82%) and by amount (96.29%) comes mainly from repudiations: they were 1.01% of claims by number but 2.74% by amount, so the claims insurers repudiated were, on average, larger than those they paid.
The report separates claims repudiated under Section 45 of the Insurance Act, which lets an insurer question a policy for fraud or misstatement only within three years of issue, from claims rejected under the policy's terms and conditions.
What This Means for Buyers
When purchasing term insurance, prioritise insurers with claim settlement ratios above 98% and a track record spanning at least 5 years. Be meticulous about health disclosure during the application process. The most dangerous mistake a term insurance buyer can make is hiding a pre-existing condition to get a lower premium. This almost guarantees claim rejection at the worst possible moment.
Consider the insurer's claims difficulty beyond the settlement ratio. Some insurers settle claims quickly with minimal documentation hassle, while others with similar settlement ratios drag the process out, causing immense stress for bereaved families. IRDAI's Master Circular on Protection of Policyholders' Interests (5 September 2024) requires a death claim to be settled within 15 days of intimation where no investigation is needed, and within 45 days where it is.
Source
IRDAI Annual Report 2024-25 (30 December 2025), Table I.11: Death Claims of Life Insurers