

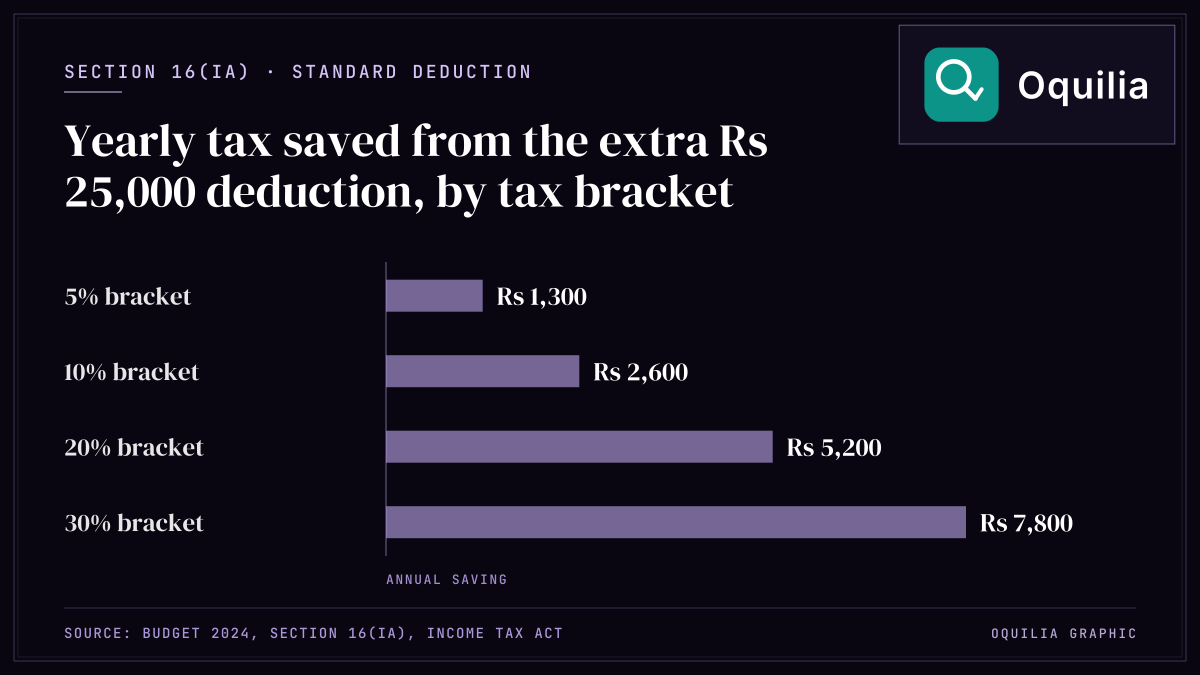
The Union Budget 2024 increased the standard deduction for salaried employees and pensioners from Rs 50,000 to Rs 75,000 for those in the new tax regime under Section 115BAC, effective from FY 2024-25 onwards. Under the old regime the deduction under Section 16(ia) stays at Rs 50,000. Both figures continue to apply in FY 2026-27. The Rs 25,000 increase translates to a direct reduction in taxable income, but the actual monetary benefit depends on the taxpayer's marginal tax rate.
Tax Saving by Income Bracket
For employees in the 5% tax bracket (taxable income between Rs 4 lakh and Rs 8 lakh under the new regime), the additional Rs 25,000 deduction saves Rs 1,300 per year (Rs 1,250 tax plus Rs 50 cess). For those in the 10% bracket (Rs 8-12 lakh), the saving is Rs 2,600. At the 20% bracket (Rs 16-20 lakh under the new regime), the annual saving rises to Rs 5,200. For top-bracket earners at 30% (above Rs 24 lakh under the new regime), the maximum annual benefit is Rs 7,800 (Rs 7,500 tax plus Rs 300 cess).
When translated to monthly take-home pay, the increase is Rs 108 to Rs 650 per month depending on the tax bracket. While the absolute amount may appear modest, the standard deduction is a flat benefit requiring no investment, documentation, or proof of expenditure. It is automatically applied by the employer during TDS computation, ensuring the benefit flows through immediately in monthly salary payments.
Interaction With the New Regime Nil-Tax Threshold
Under the new regime since Budget 2025, the nil-tax ceiling for salaried individuals is effectively Rs 12.75 lakh, not Rs 12 lakh. This is because the Rs 12 lakh threshold is the taxable income after the standard deduction of Rs 75,000. So a salaried individual with a gross salary of up to Rs 12,75,000 pays zero tax under the new regime due to the combined effect of the Rs 75,000 standard deduction and the Section 87A rebate on income up to Rs 12 lakh.
This distinction is important for employees whose salary falls close to the threshold. An employee earning Rs 12.5 lakh gross salary would have a taxable income of Rs 11.75 lakh after the standard deduction, well below the Rs 12 lakh rebate limit, and would pay zero tax. Without the enhanced standard deduction, the same employee would have taxable income of Rs 12 lakh, and the rebate would just barely apply. The Rs 75,000 standard deduction thus provides a meaningful cushion for borderline cases.
Standard Deduction for Pensioners
The standard deduction is available not only to salaried employees but also to pensioners receiving a pension from their former employer. Family pension, however, is classified as income from other sources and qualifies for a separate deduction under Section 57(iia) of one-third of the pension, capped at Rs 25,000 under the new regime and Rs 15,000 under the old regime. Senior citizens (60-80 years) and super senior citizens (above 80 years) who receive employer pension get the same standard deduction: Rs 75,000 under the new regime, or Rs 50,000 under the old regime, where they also get higher basic exemption limits.
Impact on Form 16 and ITR Filing
Employers are required to factor in the Rs 75,000 standard deduction for employees in the new regime when computing TDS on salary under Section 192. This deduction should appear clearly in Part B of Form 16 under the head "Deductions under Section 16." If you are in the new regime and your Form 16 still shows only Rs 50,000 as the standard deduction, this is an error that needs to be corrected by the employer through a revised TDS filing. When filing your ITR, verify that the standard deduction amount pre-filled from Form 16 data matches your regime: Rs 75,000 in the new regime, Rs 50,000 in the old.
For employees evaluating the old vs new regime decision, the standard deduction is Rs 75,000 under the new regime and Rs 50,000 under the old, so it tilts the comparison slightly towards the new regime. The regime choice should be based on other deductions and exemptions such as 80C, 80D, HRA, and home loan interest, which are exclusive to the old regime. Use the Oquilia Salary Breakup Calculator to see exactly how the Rs 75,000 standard deduction flows through your salary computation and affects your monthly TDS.
Source
Section 16(ia) of the Income Tax Act, Finance Act 2024, CBDT Clarification