
A borrower behind on a loan from SnapPaisa, an app operated by Ampire Finance Pvt Ltd, says the deadline was one o'clock. According to a documented borrower complaint, the message said "employment verification emails to your office from 1 PM today" would go out unless the borrower paid immediately. On the borrower's account, that hour was the point. Pay in the next few hours, or your employer hears about the loan. SnapPaisa's response is not recorded here, and the threat is described as alleged.
Update, 18 October 2026: what the Reserve Bank and the companies have since said
Ampire Finance Pvt Ltd (SalarySetu, SnapPaisa, F1SpeedLoan). The RBI's Consumer Education and Protection Cell (CEPC) recorded that the company "has acknowledged contacting the employer as per the loan agreement". It found that "a perusal of the Loan agreement reveals that there are no clauses which permit the RE to contact the employer for requesting assistance in contacting the employee/complainant/borrower or convey its message or to share his contact information. Therefore, the RE is in non-compliance of the agreed terms and conditions of the loan agreement and in non-compliance to extant regulatory guidelines". It recorded that "The action of the RE viz., unauthorized contact of the employer has been forwarded to the Department of Supervision, Central Office, RBI for necessary action". It also recorded the company's statement that "it has ceased further employee communication". Before the closure, on 8 September 2026, the company had written to the borrower, in the names of both SalarySetu and SnapPaisa: "the employer communication was initiated by our collection team".
What a 1 PM deadline actually does
Read the alleged message the way the borrower read it. It does not say the loan is overdue. It does not offer a payment plan or a date next week. It names an hour, and it names the place where the borrower earns the money being demanded.
The phrase used is "employment verification". That is a piece of ordinary office vocabulary, and that is what gives it its force. An email carrying those two words does not look like a threat when it lands in an HR inbox. It looks like routine paperwork, and it invites a reply. An email of that kind would also tell the employer, without ever using the word "debt", that an employee has borrowed money and has not paid it back.
The arithmetic of that deadline is simple and it is cruel. Whatever is in the account at noon is what there is. Nothing arrives between noon and one. So the choice on offer, on the borrower's account, is to find money that is not there or to let the workplace be contacted about the debt. Most people in that position borrow again, from another app, at a worse rate, to make the hour. That is how a single missed instalment becomes a stack of them.
If such an email is ever sent, paying afterwards does not undo it. A colleague who has read it has read it. And once a borrower has been told the office is on the table, every later call carries the same implied deadline whether or not anyone says so out loud.
The app is not the lender
SnapPaisa is an app. Ampire Finance Pvt Ltd is the company operating it. The distinction matters more than most borrowers realise, because a borrower who wants to complain needs to know which entity the regulator can actually act against.
Under the RBI's digital lending rules, in Chapter III of the Reserve Bank of India (Non-Banking Financial Companies – Credit Facilities) Directions, 2025, digital lending must run through a regulated entity. An app or a lending service provider sitting in front of that entity does not dilute its responsibility. The regulated entity remains answerable for the conduct of the platforms, the recovery agents and the outsourced staff acting on its behalf, and it must give the borrower the name and contact details of a grievance redressal officer. The same Directions require that all fees and charges appear in the Key Facts Statement given to the borrower before the loan is taken.
The practical consequence for anyone reading this: your loan agreement, not the app store listing, tells you which entity lent to you. That entity is the one you name in a complaint, and the one that carries the regulatory consequence of what its recovery contact does.
What the rules say about a threat of this kind
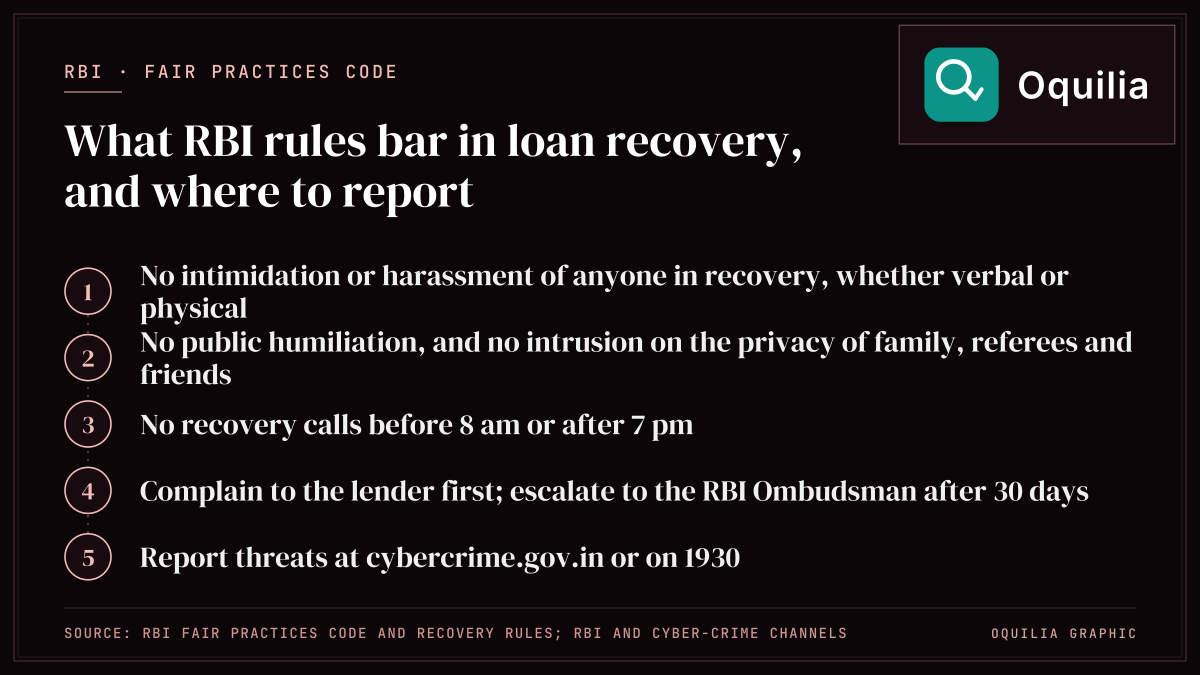
The RBI Fair Practices Code and its recovery rules are explicit on two points that bear directly on the conduct alleged here. They bar a lender and its agents from resorting to intimidation or harassment of any kind, verbal or physical, against any person in recovery. And they bar acts meant to humiliate a borrower publicly or to intrude on the privacy of family members, referees and friends. They do not name the employer. Recovery contact is confined to reasonable hours, and the responsibility for agents' conduct sits with the regulated entity, not with the agent.
A threat to contact the workplace, on the borrower's account, therefore does not become permissible because the email was framed as "verification". What matters is the purpose the contact would serve and the pressure it is designed to create.
There is a second layer. Section 351 of the Bharatiya Nyaya Sanhita, 2023 deals with criminal intimidation, which includes threatening a person with injury to their reputation in order to cause alarm or to compel them to do something they are not legally bound to do at that moment. Whether the alleged message meets that description is for the police and a court to decide on the evidence, and nothing here decides it. What a borrower should know is that a threat of this kind is not merely a customer-service dispute. It belongs on the cyber-crime portal as well as in a complaint to the regulator.
If you have been given a deadline like this
None of the following costs money, and none of it requires a lawyer.
- Save the message before you do anything else. Screenshot it with the sender's number or address and the timestamp visible. Do not reply to it, do not delete the chat, and do not uninstall the app until the evidence is out and stored somewhere else. A message threatening a specific hour is unusually strong evidence precisely because it is specific.
- Do not pay to beat the clock. A payment made under a same-day ultimatum does not close the account and does not retire the tactic. It establishes that the tactic works on you.
- Consider telling your employer first, in your own words. This is uncomfortable and it is also the single move that takes the weapon away. A short note to your manager or HR saying that a loan recovery agent may contact the office and that you are dealing with it removes the surprise the threat depends on.
- Find out who actually lent to you, then complain about them. Check the entity named in your loan agreement against the RBI's register at sachet.rbi.org.in, and file your complaint at cms.rbi.org.in. Attach the screenshot. State the date, the hour named in the message, and what was demanded.
- Report the threat separately. Use cybercrime.gov.in or call 1930. A regulatory complaint and a cyber-crime report do different jobs, and filing one does not replace the other.
- Write down every subsequent contact. Date, time, number, what was said. If your workplace is in fact contacted, ask the recipient to forward you the email intact, with its headers. That converts an allegation into a document.
Why we are naming the company
What is set out above is a borrower's documented complaint. It is an allegation, it is described as one throughout, and Ampire Finance Pvt Ltd has not given its account of the matter to us. We publish it under the company's name because a person about to install this app is entitled to find the complaint before they borrow, not after. That is the entire purpose of this piece.
We do not link to SnapPaisa, to its listing or to any download page, and we will not. A reader who is already short of money should not be one click from the loan. Naming the company in text does the work that matters.
Right of reply: Ampire Finance Pvt Ltd has a standing invitation to respond. Any correction, denial, evidence or statement it sends will be published in full and unedited alongside this article. Write to editor@oquilia.com.
Evidence · redacted copy to be published
Screenshot of a message alleged to have been sent by SnapPaisa threatening employment verification emails to the borrower's office from 1 PM
Your rights, and how to report
The lenders in this series are RBI-registered NBFCs, bound by the RBI's Fair Practices Code and recovery rules: no recovery calls before 8 am or after 7 pm, no intimidation or harassment of anyone to make you pay, no public humiliation or intrusion on the privacy of your family, referees or friends, no abuse or threats, and the all-in APR must be disclosed in the Key Facts Statement. Read the full plain-English guide on Oquilia's loan-harassment help page.
To report a lender: complain in writing to its grievance redressal officer first, escalate to the RBI Ombudsman (CMS) if there is no reply or no resolution within 30 days, check the lender's registration (and report an unregistered app) on RBI Sachet, and report threats, harassment or data misuse at the National Cyber Crime portal or on 1930. Keep every screenshot, email and call log - that record is your evidence.
More from this investigation
- PaisaInTime: ~16 missed calls in 9 minutes
- Chinmay Finlease's Lenditt: a 36.5% 'flat' rate and a 3-day rollover
- Ram Fincorp: Rs 26,901 lent, Rs 42,622 demanded - a 173% APR by its own KFS
Frequently asked questions
What should I do if a loan app threatens to email my office?
Do not pay to beat the deadline, and do not reply. Screenshot the message first, with the sender's number or address and the timestamp visible, and save it somewhere other than the phone before you uninstall anything - a threat that names a specific hour is unusually strong evidence precisely because it is specific. Then consider telling your manager or HR yourself, in your own words, that a recovery agent may contact the office and you are handling it; that removes the surprise the threat depends on. The RBI Fair Practices Code and its recovery rules bar intimidation and harassment in recovery and acts meant to humiliate you publicly or intrude on the privacy of your family, referees and friends, and the responsibility for what an agent does sits with the regulated entity named in your loan agreement, not with the app. Check that entity on the RBI register at sachet.rbi.org.in, complain about it at cms.rbi.org.in, and report the threat separately at cybercrime.gov.in or on 1930. In the complaint about SnapPaisa, which is operated by Ampire Finance Pvt Ltd, a borrower's documented account says the message warned that "employment verification emails to your office from 1 PM today" would go out unless payment was made at once; that is the allegation, and it is the kind of message a screenshot turns into a filed complaint.
Can a loan app call my office or family?
Not to pressure you. The RBI's recovery rules do not name employers, but they bar recovery agents from intimidating or harassing anyone, from acts meant to humiliate you publicly or to intrude on the privacy of your family, referees and friends, from calling before 8 am or after 7 pm, and from abuse or threats. Approaching your workplace or contacts to shame you over a loan falls outside lawful recovery, whatever an app's agreement says.
How do I report a loan app to the RBI?
Complain in writing to the NBFC's grievance redressal officer first. If it does not resolve your complaint within 30 days, escalate to the RBI Ombudsman through the Complaint Management System (cms.rbi.org.in). Use RBI Sachet (sachet.rbi.org.in) to check that the lender is registered and to report an app run by an unregistered entity. For threats or data misuse, use the National Cyber Crime portal (cybercrime.gov.in) or call 1930, and keep all screenshots and statements.
Source
Lenders' own Key Facts Statements, agreements and recovery emails; RBI Register of NBFCs; documented borrower complaints