
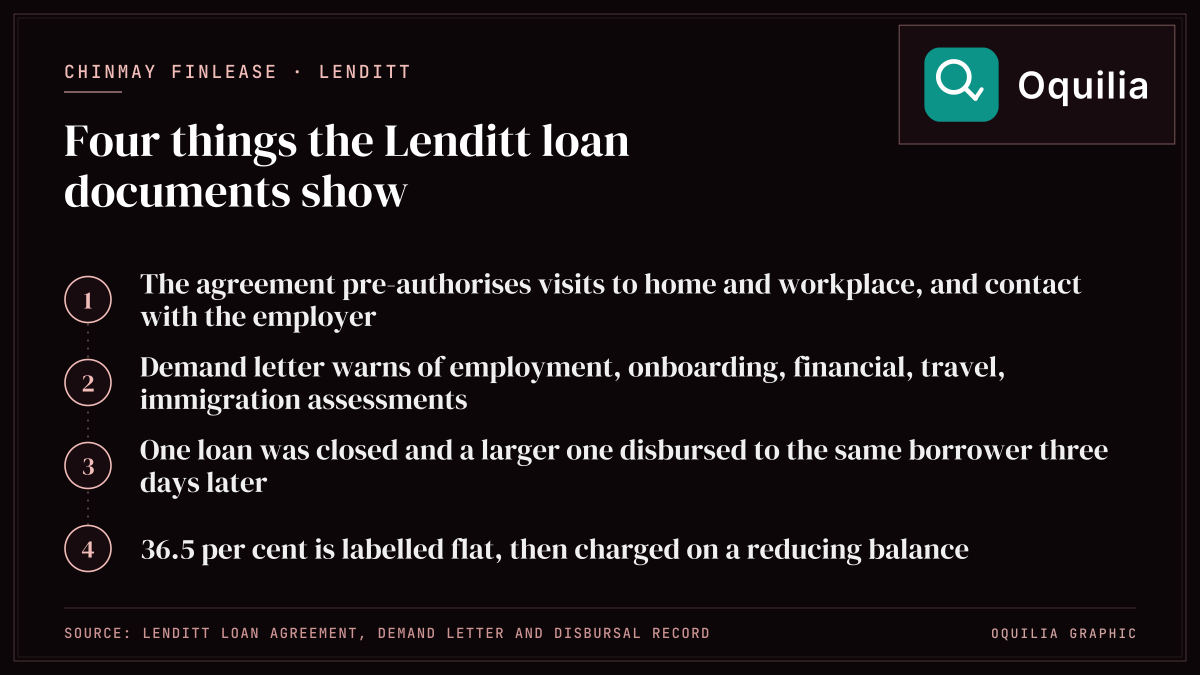
Before Chinmay Finlease Ltd released a rupee through its app "Lenditt", the borrower had already signed away the boundary between the loan and the rest of his life. The agreement pre-authorises visits to his home and to his workplace, and contact with his employer. That clause is not buried in a recovery notice sent later in anger. It is in the document he had to accept to get the money.
What that clause means once the repayment date passes
Read as a borrower reads it, at the moment the money is short. It means the people who decide whether you keep your job may be told you owe money. It means someone may arrive at the reception desk of the place you work and ask for you by name. Nobody at that office needs to be told anything further. The visit itself is the message.
A borrower can survive a bad month. What a borrower usually cannot survive is a bad month that becomes visible at work. The salary is the only thing standing between this debt and the next one, and a clause of this kind puts the salary itself inside the lender's leverage.
The demand letter that followed goes further than the agreement. It warns of consequences to the borrower's - and these are the letter's own categories - "employment, onboarding, financial, travel, immigration" assessments. That is not a warning about a credit score. Onboarding is a new job. Travel and immigration are a passport and a visa. The letter puts a borrower's ability to be hired abroad, or to leave the country at all, on the list of things at stake over a short-tenure loan.
Three days between one loan closing and a larger one opening
The lending record shows something separate and, over time, more expensive. One short loan was treated as closed. Three days later, a fresh and larger loan was disbursed to the same borrower.
That is a rollover, and the arithmetic of a rollover is what makes short-tenure lending hard to leave. The first loan is never repaid out of income; it is repaid out of the second loan. The principal goes up. The clock starts again. Each cycle takes a new set of charges, and the borrower's own bank statement shows a closure that never actually happened - money went out and came back in, larger, within seventy-two hours. A borrower who believes he has cleared one loan and started another has in fact never been out of debt for a single day.
This matters in a dispute. If the same borrower is later told he defaulted, the disbursal and closure dates in his bank statement are the record of how the balance grew, and they are held by his bank, not by the lender.
"Flat" is not what the agreement does
The agreement puts the figure of 36.5 per cent next to the word "flat", and then charges it on a reducing balance. Flat and reducing balance are two different methods of computing interest. They do not describe the same loan, and a borrower shown the word "flat" has been given a label that does not match what the contract actually performs. The framing understates what the loan costs.
The RBI's digital lending rules, first issued in September 2022 and now in Chapter III of the Reserve Bank of India (Non-Banking Financial Companies – Credit Facilities) Directions, 2025, exist precisely because of this. A digital lender must give the borrower a Key Facts Statement before the loan is taken, and that statement must carry a single all-in annualised cost - every charge, fee and deduction included - in one number the borrower can compare against any other loan. A percentage described as "flat" in a clause is not that disclosure. If your Key Facts Statement does not carry an all-in annual figure, or if the figure there does not match what you were told in the app, that gap is itself something you can put in front of the regulator.
What a signature can and cannot buy
A pre-written permission to visit a workplace or to contact an employer does not create a right the lender would not otherwise have. The RBI Fair Practices Code requires recovery to be free of harassment, restricts contact to reasonable hours, and bars conduct that humiliates a borrower or intrudes on the privacy of the borrower and the people around them. Contacting an employer to apply pressure sits squarely inside what the Code prohibits. A clause a borrower had no realistic ability to negotiate does not license conduct the regulator has already barred, and the RBI holds the regulated lender responsible for recovery carried out in its name, including by anyone acting on its behalf.
The demand letter is a separate question again. Where a demand goes beyond stating credit consequences and warns of harm to a person's employment or their ability to travel, whether that amounts to criminal intimidation under section 351 of the Bharatiya Nyaya Sanhita, 2023 is a matter for the police to assess on the document. It is not a matter for the lender to decide by writing a clause.
What you can do this week, at no cost
- Save the paperwork before you do anything else. Screenshot the clause pre-authorising home and workplace visits and employer contact. Save the demand letter, in particular the line listing employment, onboarding, financial, travel and immigration. Export the loan agreement as a PDF. These are the lender's own words and they are the strongest thing you hold.
- Pull your bank statement for the disbursal dates. Download the statement covering the closure of the first loan and the disbursal of the larger one three days later. Mark both entries. This is independent evidence from your bank of how the balance actually moved.
- Get ahead of the workplace contact. If you fear a visit or a call to your employer, a short factual note to your manager or HR - that you have a personal loan in dispute and a lender may contact the office - removes almost all of the leverage. The threat works only while it is a secret.
- Complain to the RBI. File at cms.rbi.org.in. Attach the clause, the demand letter and the disbursal dates. Say plainly what you want examined: recovery conduct directed at your workplace, and the cost disclosure you were given.
- Report the demand letter if it threatens you. Use cybercrime.gov.in or call 1930. Upload the letter itself rather than describing it.
- Check who the lender on your paperwork actually is. An app is not a lender. Look up the entity named in your agreement on the RBI register at sachet.rbi.org.in. If no registered entity is named anywhere in your documents, report that too.
- Do not take the next loan to close this one. A larger loan three days after the last one is the mechanism, not the way out. If you cannot pay, say so in writing and keep the reply.
Why we name Chinmay Finlease Ltd
Everything set out above comes from documents the company itself produced - the Lenditt loan agreement, the demand letter and the disbursal record - and from published RBI requirements. We are not repeating an allegation we cannot see. We name Chinmay Finlease Ltd because someone typing "Lenditt" into a search box at eleven at night, with a repayment due and a decision to make, deserves to find the clause before they sign it rather than after. We do not link to the app or to the company, and we will not. Sending a reader who is already short of money one click nearer to the thing is the opposite of the reason this piece exists.
Right of reply: Chinmay Finlease Ltd has a standing invitation to respond. Any correction, any document, or any statement about its recovery practices, its cost disclosure or the three-day disbursal will be published in full and unedited alongside this article. Write to editor@oquilia.com.
Evidence · redacted copy to be published
Lenditt loan agreement clauses pre-authorising home and workplace visits and contact with the borrower's employer
Your rights, and how to report
The lenders in this series are RBI-registered NBFCs, bound by the RBI's Fair Practices Code and recovery rules: no recovery calls before 8 am or after 7 pm, no intimidation or harassment of anyone to make you pay, no public humiliation or intrusion on the privacy of your family, referees or friends, no abuse or threats, and the all-in APR must be disclosed in the Key Facts Statement. Read the full plain-English guide on Oquilia's loan-harassment help page.
To report a lender: complain in writing to its grievance redressal officer first, escalate to the RBI Ombudsman (CMS) if there is no reply or no resolution within 30 days, check the lender's registration (and report an unregistered app) on RBI Sachet, and report threats, harassment or data misuse at the National Cyber Crime portal or on 1930. Keep every screenshot, email and call log - that record is your evidence.
More from this investigation
- Ram Fincorp: Rs 26,901 lent, Rs 42,622 demanded - a 173% APR by its own KFS
- Zayloloan: 1% a day and a 458% APR - one firm, four apps
- Rupee On Time: an effective rate of about 635% a year
Frequently asked questions
Can a loan agreement let the lender visit my office or contact my employer?
A clause can say so, but it cannot buy the lender a right the regulator has already removed. Chinmay Finlease Ltd's Lenditt agreement pre-authorises visits to a borrower's home and workplace and contact with the borrower's employer. The RBI Fair Practices Code separately requires recovery to be free of harassment and bars conduct that humiliates a borrower or intrudes on the privacy of the borrower and the people around them, and contacting your employer to apply pressure sits inside that bar. Your signature on a document you had no realistic ability to negotiate does not license conduct the Code prohibits, and the RBI holds the regulated lender answerable for recovery carried out in its name. If a demand letter also warns of consequences to your employment or your ability to travel, whether that crosses into criminal intimidation under section 351 of the Bharatiya Nyaya Sanhita, 2023 is for the police to assess on the document itself. Practically: screenshot the clause and save the letter, tell your manager or HR yourself before anyone else does, complain to the RBI at cms.rbi.org.in with the documents attached, and report a threatening letter at cybercrime.gov.in or on 1930.
Can a loan app call my office or family?
Not to pressure you. The RBI's recovery rules do not name employers, but they bar recovery agents from intimidating or harassing anyone, from acts meant to humiliate you publicly or to intrude on the privacy of your family, referees and friends, from calling before 8 am or after 7 pm, and from abuse or threats. Approaching your workplace or contacts to shame you over a loan falls outside lawful recovery, whatever an app's agreement says.
How do I report a loan app to the RBI?
Complain in writing to the NBFC's grievance redressal officer first. If it does not resolve your complaint within 30 days, escalate to the RBI Ombudsman through the Complaint Management System (cms.rbi.org.in). Use RBI Sachet (sachet.rbi.org.in) to check that the lender is registered and to report an app run by an unregistered entity. For threats or data misuse, use the National Cyber Crime portal (cybercrime.gov.in) or call 1930, and keep all screenshots and statements.
Source
Lenders' own Key Facts Statements, agreements and recovery emails; RBI Register of NBFCs; documented borrower complaints