

The Central Board of Direct Taxes (CBDT) has notified the updated Income Tax Return forms for Assessment Year 2026-27, applicable to income earned during Financial Year 2025-26. The filing window opened on 1 April 2026, and the deadline for individuals and HUFs not subject to audit is 31 July 2026. The forms incorporate the revised new regime slab structure, the enhanced standard deduction of Rs 75,000, and a streamlined capital gains schedule reflecting the uniform 12.5% LTCG rate.
Which ITR Form Should You File?
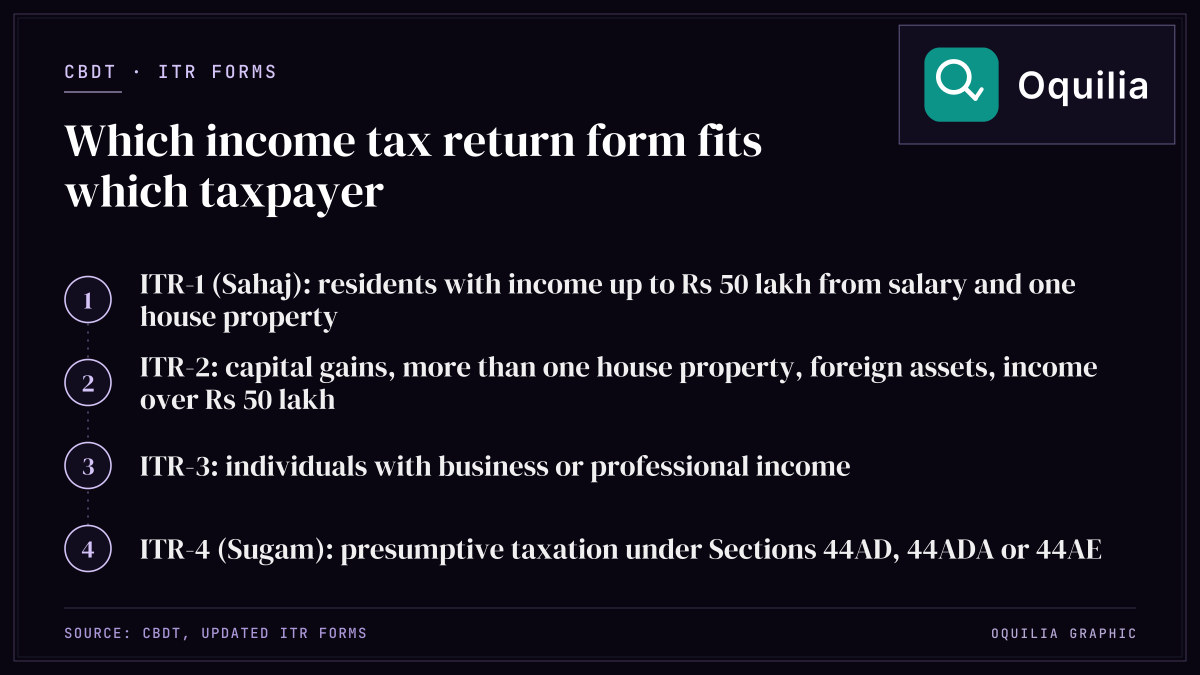
ITR-1 (Sahaj) is the simplest form, applicable to resident individuals with total income up to Rs 50 lakh from salary, up to two house properties, other sources (interest, dividends), long-term capital gains under Section 112A of up to Rs 1.25 lakh, and agricultural income up to Rs 5,000. ITR-2 is for individuals and HUFs with other capital gains, more than two house properties, foreign assets, or income exceeding Rs 50 lakh. ITR-3 is for individuals with business or professional income. ITR-4 (Sugam) applies to those opting for the presumptive taxation scheme under Sections 44AD, 44ADA, or 44AE.
A common mistake is salaried individuals with mutual fund capital gains filing ITR-1 instead of ITR-2. If you redeemed mutual fund units during FY 2025-26 with any short-term gain, any loss, or long-term gains above Rs 1.25 lakh, you must file ITR-2 and report the transactions in the capital gains schedule. Filing the wrong form can lead to a defective return notice under Section 139(9).
New Regime as Default: What to Remember
Since FY 2023-24, the new tax regime under Section 115BAC is the default regime. If you wish to opt for the old regime, you must explicitly select it in the ITR form. Salaried individuals who informed their employer about the old regime choice for TDS purposes must still confirm the same in the ITR. The selection made in the ITR is final and overrides the employer declaration. For individuals without business income, the regime can be switched freely each year at the time of filing.
Individuals with business or professional income who wish to opt out of the new regime must file Form 10-IEA before the due date of the return. Once they switch to the old regime, they can switch back to the new regime only once in their lifetime. This restriction does not apply to salaried individuals.
Five Common Filing Mistakes to Avoid
First, not reconciling Form 26AS and AIS (Annual Information Statement) with your return. The Income Tax Department now has comprehensive data on bank interest, dividends, mutual fund transactions, property purchases, and high-value spending. Any mismatch between AIS data and your ITR will trigger a notice. Second, forgetting to report exempt income such as LTCG up to Rs 1.25 lakh, agricultural income, or dividend income from domestic companies (which is now taxable but often omitted).
Third, claiming HRA exemption without proper rent receipts and the landlord's PAN (mandatory if annual rent exceeds Rs 1 lakh). Fourth, not carrying forward capital losses by filing after the due date. Capital losses can only be carried forward for set-off against future gains if the ITR is filed by 31 July. Fifth, selecting the wrong assessment year. Every year, thousands of returns are filed under the wrong AY, requiring rectification proceedings that delay refunds.
E-Verification and Refund Timeline
After filing, the return must be e-verified within 30 days. The fastest method is Aadhaar OTP verification, which takes under a minute. A return verified after 30 days is treated as filed on the date of verification, with the consequences of late filing, and a return that is never verified is treated as invalid. Once verified and processed by CPC Bengaluru, refunds are typically issued within 30-45 days for straightforward returns. The refund is credited directly to the bank account linked with PAN, and interest under Section 244A is payable on delayed refunds at 0.5% per month from 1 April of the assessment year if the return was filed by the due date, or from the date of filing if it was filed late.
Source
CBDT Notification No. 45/2026, Income Tax Department e-Filing Portal