

Update, 17 November 2026: from 1 April 2026 (tax year 2026-27) the HRA exemption is in Schedule III (Sl. No. 11) of the Income-tax Act, 2025, computed under rule 279 of the Income-tax Rules, 2026, which lists Hyderabad, Pune, Ahmedabad and Bengaluru with Mumbai, Kolkata, Delhi and Chennai as places where the third limit is 50% of salary. The deduction for rent paid without HRA (old section 80GG) is section 134, declared in Form No. 31 (formerly Form 10BA). Both are available only under the old regime.
House Rent Allowance (HRA) exemption under Section 10(13A) is one of the largest tax-saving components available to salaried employees under the old tax regime. Yet a significant number of taxpayers either fail to claim the full eligible amount or make computational errors that result in overpayment of tax. For an employee earning Rs 12-15 lakh annually and paying rent of Rs 25,000 per month in a metro city, the HRA exemption can reduce taxable income by Rs 1.5-2 lakh, translating to a tax saving of Rs 45,000-60,000. Getting this calculation wrong is an expensive mistake.
The Three-Way HRA Formula
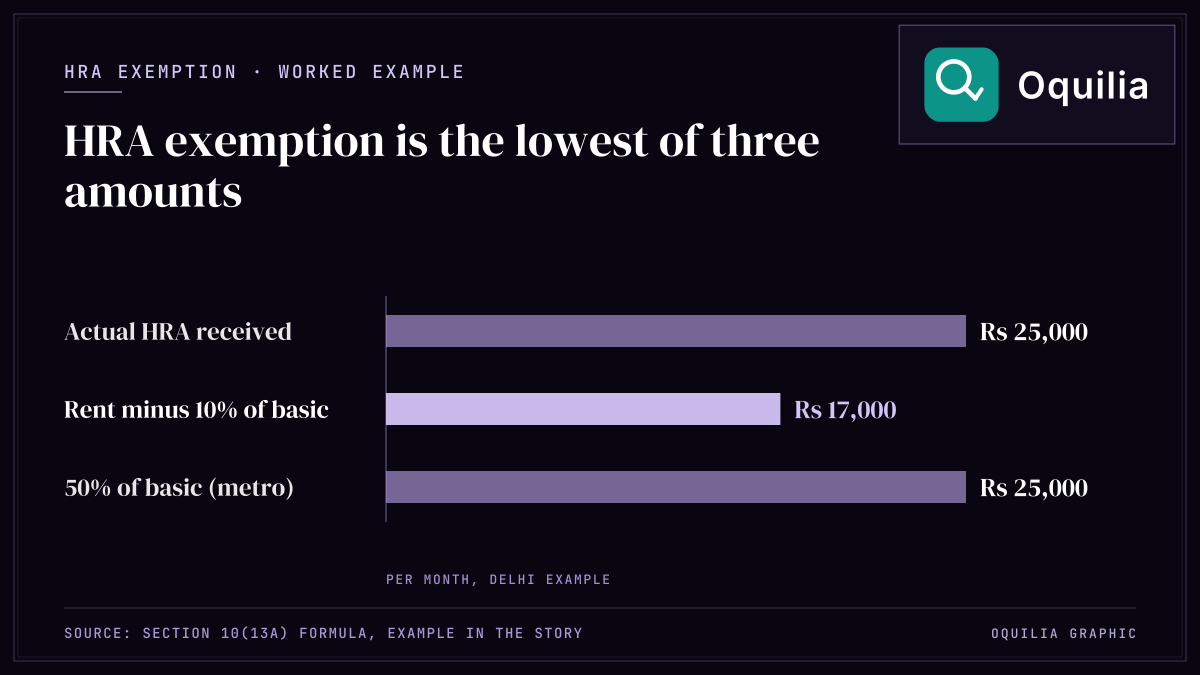
The HRA exemption is the minimum of three amounts: first, the actual HRA received from the employer as stated in the salary slip; second, rent paid minus 10% of basic salary (basic + dearness allowance); and third, 50% of basic salary if the employee resides in a metro city (Delhi, Mumbai, Chennai, or Kolkata) or 40% of basic salary for non-metro cities. The exemption is calculated on a monthly basis, which means changes in rent, salary, or city of residence during the year must be accounted for month by month.
Consider an employee with a basic salary of Rs 50,000 per month, HRA of Rs 25,000, living in Delhi and paying rent of Rs 22,000. The three amounts are: Rs 25,000 (actual HRA), Rs 17,000 (rent minus 10% of basic: 22,000 minus 5,000), and Rs 25,000 (50% of basic for metro). The exemption is the minimum, which is Rs 17,000 per month or Rs 2,04,000 per year.
Common Mistake 1: Not Claiming for Part of the Year
Many employees who relocate mid-year or change from a rented accommodation to an owned property (or vice versa) fail to bifurcate the HRA calculation. If you lived in a rented flat in Mumbai from April to September and then moved to your own house in Pune from October onwards, you can still claim HRA exemption for the six months you paid rent. The employer's Form 16 often calculates HRA exemption for the full year based on the declaration submitted at the start, which may not reflect mid-year changes. You should recompute and claim the correct amount in your ITR.
Common Mistake 2: Metro vs Non-Metro Confusion
The 50% of basic salary limit applies only to Mumbai, Delhi, Chennai, and Kolkata. All other cities, including Bengaluru, Hyderabad, Pune, and Gurugram, are classified as non-metro for HRA purposes, where the limit is 40% of basic salary. Employees in Gurugram or Noida often assume the 50% limit applies because of proximity to Delhi, but this is incorrect. The classification is based on the actual city of residence, not the employer's registered office location.
Common Mistake 3: Missing Landlord PAN Requirement
If the total annual rent paid exceeds Rs 1,00,000, the employee must provide the landlord's PAN to the employer. Failure to furnish the PAN can result in the employer not allowing the HRA exemption during TDS computation, and the department may disallow the claim during assessment. For rent paid to a parent (a legitimate tax-planning strategy), the parent must declare the rental income in their own ITR. If the parent is in a lower tax bracket or has no other income, this arrangement saves tax on a household basis.
Common Mistake 4: Not Claiming When Employer Does Not Pay HRA
Employees whose salary structure does not include an HRA component can still claim a deduction under Section 80GG of up to Rs 5,000 per month (Rs 60,000 per year), subject to conditions. This applies to self-employed individuals as well. To claim 80GG, neither you nor your spouse, minor child or HUF may own a home at the place where you live or work, you must not claim a self-occupied home elsewhere, you must file a declaration in Form 10BA, and the deduction is limited to 25% of total income or rent paid minus 10% of total income, whichever is lower.
Under the old regime, ensuring your HRA calculation is accurate is one of the simplest ways to save a significant amount of tax. Use the Oquilia HRA Calculator to input your monthly salary components and rent to get the precise exemption figure for each month of the year.
Source
Section 10(13A) of the Income Tax Act, 1961 and rule 2A of the Income Tax Rules, 1962 (Schedule III, Sl. No. 11 of the Income-tax Act, 2025 and rule 279 of the Income-tax Rules, 2026 from 1 April 2026)